 QLD Broker of the Year
Brisbane Construction Loans: Finance Your Build From Slab to Handover
Building your next home comes with its own finance rules, progress payments, valuation risk and a builder’s contract to align with your lender. MC Mortgage Solutions structures construction loans for Brisbane builds, comparing 30+ lenders and managing every drawdown from slab to handover, at no cost to you.
About Us, Trusted Construction Finance Specialists for Brisbane Builds
Every build starts with the same question: will the numbers actually work? MC Mortgage Solutions has been answering that question for Brisbane homeowners since 2007, long before the first sod is turned.
We’ve sat across the table from enough builders, valuers and lenders to know exactly where construction finance goes wrong, and how to structure it so it doesn’t. That’s 25 or more years of combined lending experience, applied to your specific project.
Brisbane clients trust us with their build for a reason: a 5.0-star rating from 190 verified Google reviews, and a panel of 30+ lenders we compare on construction policy, not just headline rates.
Construction Project Loan Scenarios We Structure
Building on Land You Already Own
Your land equity often does more heavy lifting than people expect. We work out how much of it can offset your construction deposit before you finalise a builder.
House and Land Packages
Two contracts, one settlement, and a lender who needs both to line up. We coordinate the land purchase and the build finance so nothing stalls between them.
Knockdown Rebuilds
Your existing mortgage doesn’t disappear just because the house does. We structure demolition costs, land value and completed value as three separate pieces that still need to add up for your lender.
Renovations That Need Progressive Funding
Once a renovation is substantial enough to need staged payments, it’s treated like a build, not a top-up. We set it up on the same drawdown structure as new construction.
Owner-Builder Finance
Most lenders won’t touch it. We know which ones on our panel will, and what conditions they’ll attach before you commit to managing the build yourself.
Protecting You From a Valuation Shortfall
We run indicative valuations across multiple lenders before your contract is locked in, so if the numbers won’t stack up, you find out early enough to do something about it.
How a Construction Loan Actually Works
A construction loan doesn’t hand you the full amount at settlement like a standard home loan. Your lender releases funds directly to your builder in stages, known as progress payments, as each part of the build is completed and inspected. You pay interest only on the amount drawn down so far, which keeps repayments lower while your home is being built.
Most Brisbane construction loans follow a five-stage structure: slab, frame, lock-up, fit-out, and completion. Each stage draws a different share of the total loan, and your lender typically requires a signed invoice from your builder, sometimes a valuer’s inspection, before releasing the next payment. Once the final payment is made, your loan switches to standard principal and interest repayments.
The Valuation Risk Most Buyers Don’t See Coming
Before approving a construction loan, your lender orders an “as-if-complete” valuation, an estimate of what your finished home will be worth, based on your plans and building contract, not what an empty block is worth today. For buyers exploring Home Loans Brisbane, this valuation is an important part of assessing the overall project.
This valuation doesn’t always match your contract price. If it comes in lower than your combined land and construction cost, you have a valuation shortfall, and you’ll typically need extra cash, a restructured loan, or a reduced project scope. This happens more often in new estates with limited comparable sales, or with highly customised builds.
We arrange indicative valuations across more than one lender before you commit to a contract, so a shortfall is identified early, not after you’ve signed.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
How We Manage Your Construction Loan From First Call to Final Payment
Review Land and Contract
We review your land position, builder, and contract structure before we touch a lender, so we know exactly what we’re financing before we compare anyone.
Shortlist Suitable Lenders
Not every lender on our panel handles construction well, so we match your project to the ones whose policy genuinely fits new builds, rebuilds or renovations.
Test the Valuation
We arrange indicative valuations across more than one lender before your contract is final, so a funding gap shows up early, not after you’ve signed.
Lock In Pre-Approval
We lodge your application and secure a confirmed budget, so you can sign your building contract knowing the finance is already sorted.
Manage Progress Payments
As each stage completes, we coordinate the builder’s invoice, any required valuation, and the drawdown request directly with your lender.
Confirm Loan Transition
Once your final payment clears and your certificate of completion lands, we check your loan has correctly switched to ongoing principal and interest.
Why Brisbane Builders Trust MC Mortgage Solutions With Their Home Building Loan
25+ Years of Lending Experience
We’ve structured construction and progressive drawdown finance for Brisbane builds for over two decades, across new builds, rebuilds and renovations alike.
30+ Lenders Compared on Construction Policy
Your current bank is one option among many; we match you to whichever lender’s construction policy genuinely suits your project.
A Free Service, Paid by the Lender
There’s no cost to work with us; the lender pays our commission, so our advice stays focused on getting your build funded correctly.
We Manage Every Drawdown, Not Just the Approval
We coordinate progress payments with your builder and lender throughout the entire build, not only at the pre-approval stage.
A 90% Client Referral Rate
Most of our construction clients come to us through referrals from builders and past clients we’ve already guided through a build.
A 5.0 Star Rating From 190 Verified Reviews
Local Brisbane bayside knowledge, backed by a genuine track record from clients we’ve helped from Manly to the Redlands.
Speak With a Construction Finance Broker Before You Sign Anything
Book a free, no-obligation chat, and we’ll tell you in one conversation what you can borrow and whether your build stacks up before you sign a contract.
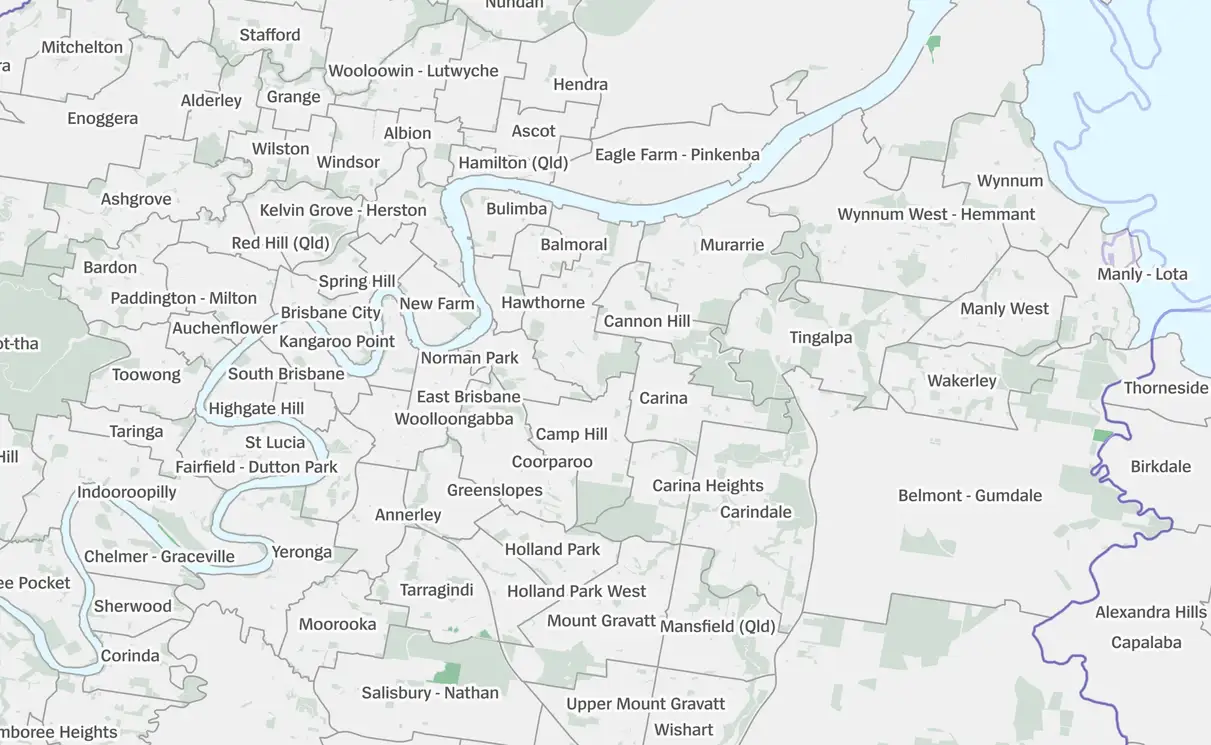
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Licensed, Experienced and Building-Ready
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating on Brisbane’s bayside since 2007. Brokers with 15–25+ years of lending experience each. |
| Best-interests duty | As a mortgage broker, we’re bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Get Your Build Fully Financed Before You Break Ground
Your builder needs a contract. Your lender needs a valuation that stacks up. We make sure both are sorted before you commit to either. MC Mortgage Solutions compares 30+ Brisbane lenders and manages your construction loan from pre-approval through every progress payment to final completion, at no cost to you.
Our All Services
Construction lending is one part of what we do. Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFrequently Asked Questions (FAQs)
Common questions about progress payments, valuation shortfalls, deposits and building contracts for a Brisbane construction loan. If yours is not here, ask us directly.
How do progress payments work on a construction loan?
Your lender pays your builder directly at each completed stage: slab, frame, lock-up, fit-out and completion, generally after receiving a signed invoice and sometimes a valuation.
What is a valuation shortfall and how common is it?
A valuation shortfall happens when your lender’s “as-if-complete” valuation comes in lower than your land and building contract cost combined. It’s a genuine risk on new builds, particularly in new estates or with highly customised homes.
How much deposit do I need for a construction loan in Brisbane?
Typically 5% to 20% depending on the lender, your valuation outcome, and eligibility for government schemes. This is separate from your builder’s deposit, capped by QBCC rules.
Can I use the First Home Owner Grant for my construction deposit?
Generally no. The grant is usually released after your first progress payment at the slab stage, not before.
What’s the difference between a fixed-price and cost-plus building contract?
A fixed-price contract sets a total cost upfront, which most lenders require. A cost-plus contract bills for actual costs as they’re incurred, and most lenders won’t fund it.
Can I get a construction loan as an owner-builder?
Fewer lenders offer owner-builder construction finance, and those that do apply stricter conditions. We identify which lenders on our panel will consider your project.
What happens to my repayments once the build is finished?
Once your final progress payment is made and your certificate of completion is issued, your loan switches from interest-only to standard principal and interest repayments.
Can I include land purchase in my construction loan?
Yes, many lenders allow the land purchase and construction costs to be combined into a single loan.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902