 QLD Broker of the Year
Brisbane Home Loan Refinancing: Get a Better Rate
Compare 30+ lenders before you refinance. We check the real cost, your bank’s retention offer, and the cashback catches first, at no cost to you.
About MC Mortgage Solutions: Refinance Specialists in Greater Brisbane
MC Mortgage Solutions is based in Manly, QLD, and has been providing home loan refinancing services across Greater Brisbane since 2007. Home loan pricing rewards new customers more than loyal ones, and refinancing is where that gap actually costs Brisbane homeowners money.
We arrange home loan refinancing for Brisbane homeowners, comparing your current loan against the market, negotiating with your existing bank’s retention team, and moving you to a better structure when the numbers genuinely support it.
We read which lenders are quietly overcharging existing customers, work out your break-even point before recommending a move, and know a genuine bank counteroffer from a stalling tactic. We work with homeowners across Greater Brisbane, including Manly, Wynnum, Lota and the Redlands.
Who We Serve: Home Loan Refinancing Across Greater Brisbane
Refinancing suits different homeowners for different reasons. We work with Brisbane borrowers who want to know if a move is worth it before they make one.
Homeowners Coming Off a Fixed Rate
Your fixed term ends and the loan rolls onto your lender’s standard variable rate, often well above what new customers are offered. We line up your options before that happens, not after the higher repayment lands.
Long-Term Customers Paying More Than New Ones
Loyalty rarely gets rewarded with a better rate. If you have not repriced or reviewed your loan in a couple of years, there is a good chance you are funding someone else’s introductory offer.
Homeowners Consolidating Debt
Credit cards and personal loans carry rates well above a mortgage. We look at whether folding higher-interest debt into your home loan genuinely reduces what you pay overall, not just your monthly repayment.
Homeowners Releasing Equity
Renovations, a car, or a deposit for your next property. We work out how much equity you can access and what a cash-out refinance actually costs, alongside our investment loans options if the plan is another purchase.
Homeowners Wanting Better Loan Features
An offset account, a redraw facility, or simply fewer fees. Loan features change fast, and what your bank offered when you signed up is often behind what is now standard.
Self-Employed Homeowners
Refinancing with updated financials is not the same process as your original purchase. We know how lenders read a self-employed refinance application and which ones will actually work with your current numbers.
Is Refinancing Actually Worth It? The Real Cost vs Saving Question
Refinancing typically costs somewhere between $500 and $2,000 in total, once every fee is added up. A rate cut that saves you $50 a month is not worth that outlay for a year or more. A rate cut that saves you $200 a month usually is.
The only number that matters is how long it takes your savings to cover the switching cost, and that depends on your loan balance, the rate gap, and which fees your new lender is willing to waive. We work that figure out before you apply, not after you have paid to find out.
What Refinancing Actually Costs
| Fee | Typical range | Who charges it |
|---|---|---|
| Discharge or exit fee | $150 to $500 | Your current lender |
| New loan application fee | $0 to $750, often waived | Your new lender |
| Property valuation | $50 to $600, often free on refinance deals | New lender or valuer |
| Mortgage registration and discharge | Roughly $200 to $250 each | Queensland Titles Registry |
| Break cost | Variable, only on fixed-rate loans | Your current lender |
Exit fees on variable-rate loans have been banned by law since July 2011, so if your loan is variable, discharge and government fees are usually the only cost on your current lender’s side. A fixed-rate loan is different, breaking it early can still trigger a break cost, and we calculate that figure before recommending you exit one.
The Cashback Trap: Why the Biggest Offer Is Not Always the Best Deal
Refinance cashback offers in Australia currently run from around $1,000 to $4,000, usually on loans of $250,000 or more, and usually capped at 80% LVR. They are real money, but they come with two catches worth knowing before you chase the biggest number.
The Claw-Back Clause
Most cashback offers carry a claw-back clause. If you refinance again within 12 to 24 months, you may have to repay the lot.
A Higher Rate Eats It
A 0.3% rate difference on a $600,000 loan costs roughly $1,800 a year, which wipes out a $3,000 cashback well before the clawback period even ends.
When Refinancing Makes Sense, and When It Does Not
It usually makes sense when
- Your fixed rate is ending and about to roll onto a much higher variable rate
- Your current rate is materially above what the market is offering for your loan size and LVR
- You want to access equity for a renovation, investment deposit, or major expense
- You are consolidating higher-interest debts like credit cards or personal loans into your mortgage
- Your income or circumstances have improved enough to qualify for a meaningfully better rate tier
It makes less sense when
- You are still inside a fixed-rate break cost period
- The switching cost outweighs the saving inside a realistic timeframe
- Your LVR has crept above 80% since you bought, which can mean paying LMI again on the new loan
What Happens to Your Equity and LVR When You Refinance
Your new loan is assessed against your property’s current value, not what you originally paid. If your property has grown in value and your loan balance has shrunk, your loan to value ratio (LVR) may now sit comfortably under 80%, opening up sharper rates and removing any LMI requirement.
If the opposite has happened, values have flattened or you are refinancing to pull out equity, your LVR can end up higher than expected, which may mean LMI applies again even though you did not pay it on your original loan. We check this before you apply, using a current valuation estimate, not the purchase price from years ago.
We Also Check What Your Current Bank Will Offer to Keep You
Around 72% of people who threaten to refinance are offered a better deal by their existing lender to stay. That is not a reason to avoid refinancing, it is a reason to get a genuine competing offer in hand first.
- We run the comparison across 30+ lenders and give you a real number to take back to your bank
- Or a clear reason to leave if their retention offer still does not stack up
- Either way, you are negotiating with actual alternatives, not a bluff
Our refinance mortgage Brisbane page covers the wider refinancing service, including investment and commercial loans.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
What to Expect Once You Start Your Refinance
Free Review
We look at your current loan, rate, and LVR, and tell you honestly whether refinancing is likely to be worth it before anything is submitted.
Lender Comparison
We compare rate, fees, cashback and policy across 30+ lenders, including whether your current bank’s retention offer beats them all.
Application and Settlement
We manage the new application, the discharge of your old loan, and the settlement timing, so there is no gap where you are paying two loans at once.
Why Choose MC Mortgage Solutions for Home Loan Refinancing in Brisbane
Break-Even Analysis First
We calculate your break-even point before recommending you switch, spend, or stay.
Two Decades Experience
25+ years of combined lending experience spotting which lenders are quietly overcharging existing customers.
Real Retention Numbers
We factor in your current bank’s likely retention offer, so you negotiate with real numbers.
Free To You
Our service costs you nothing, because the lender pays our commission, and we are legally bound to act in your best interests.
Seamless Settlement Timing
We manage the settlement timing so your old and new loans do not overlap and cost you extra interest.
Total Cost Comparison
We compare lenders on total cost, not just the headline rate or the cashback figure.
Speak to a Brisbane Refinance Specialist
Book a free, no obligation review, and we will tell you honestly whether refinancing is worth it for your situation before you spend a dollar on it.
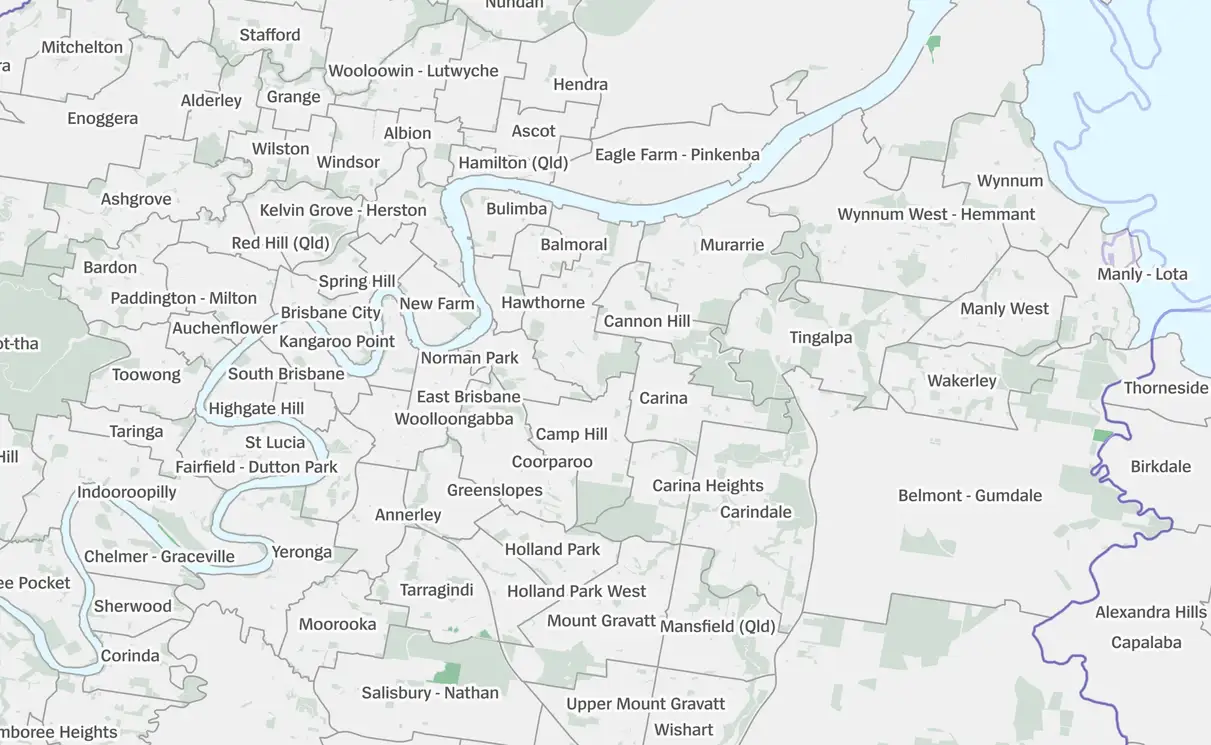
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed & Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating on Brisbane’s bayside since 2007. Brokers with 25+ years of lending experience each. |
| Best-interests duty | As a mortgage broker, we are bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Find Out What Refinancing Would Actually Save You
Not what a cashback banner promises, what it actually saves once every fee, break cost and rate difference is accounted for. MC Mortgage Solutions compares 30+ Brisbane lenders and manages your refinance from the first comparison through to settlement, at no cost to you.
Our All Services
Refinancing is one part of what we do. Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFrequently Asked Questions (FAQs)
Common questions about break-even maths, exit fees, cashback offers, equity and how long a Brisbane refinance takes. If yours is not here, ask us directly.
Is it worth refinancing for a 0.5% rate reduction?
Usually yes. On a $600,000 loan, a 0.5% cut saves roughly $3,000 a year, which clears a typical $500 to $2,000 switching cost within months. Below about 0.2%, the maths gets tighter and depends heavily on your specific fees.
Will my bank charge me an exit fee to refinance?
Not if your loan is variable. Exit fees on variable-rate loans have been banned by law since July 2011. A fixed-rate loan is different and can still attract a break cost if you leave before the term ends.
Is a $3,000 cashback offer better than a lower rate elsewhere?
Not necessarily. A rate that is even 0.3% higher on a $600,000 loan costs about $1,800 a year, so a cashback can be erased within two years, and most cashback offers require repayment if you refinance again within 12 to 24 months.
Do I need 20% equity to refinance in Brisbane?
Not strictly, but staying at or under 80% LVR gets you the sharpest rates and avoids LMI. Above that, your lender options narrow and LMI may apply on the new loan even if you did not pay it originally.
Should I refinance or ask my bank to match a better rate?
Ask, but only after you have a genuine competing offer. Around 72% of people who threaten to leave are given a better deal to stay, so we get you a real alternative first, rather than a bluff your bank can see through.
Can refinancing pay off my credit cards and personal loans?
Yes. Rolling higher-interest debts into your mortgage usually lowers your monthly repayment, though it can extend how long you are paying that debt off overall, which we model before recommending it.
How long does a Brisbane refinance take from application to settlement?
Usually 3 to 4 weeks, depending on how quickly your new lender processes the valuation and your current lender processes the discharge.
What happens if my property’s value has dropped since I bought it?
Your LVR is recalculated against the current valuation, so a lower value can push your LVR above 80%, which may mean LMI applies or your rate options narrow. We check this before you commit to switching.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902