 QLD Broker of the Year
Home Loan Pre-Approval Brisbane: A Real Number, Not an Estimate
Get a credit-checked pre-approval, not a rough online guess. Matched across 30+ lenders and ready in 3 to 5 business days, at no cost to you.
Who We Are: Brisbane Mortgage Brokers Who Get Pre-Approval Right
MC Mortgage Solutions has arranged home loan financing from Manly, in Greater Brisbane, since 2007. Pre-approval is where most new client relationships start, and getting it right the first time, rather than handing over a guess that falls apart later, is what we take most seriously.
We arrange pre-approval for first home buyers doing their first credit check, self-employed buyers with financials to explain, guarantor-backed buyers, and investors managing existing debt.
We know which lenders apply the APRA servicing buffer more conservatively, which assess self-employed and gig income fairly, and which turn around a full, credit-checked answer fastest, so your application goes to the right lender the first time. We work with buyers across Greater Brisbane, including Manly, Wynnum, Lota and the Redlands.
Who We Serve: Home Loan Pre-Approval Across Brisbane, QLD
Pre-approval means something different depending on why you need it. We help a wide range of Brisbane buyers get a real, credit-checked number before they start making offers.
First Home Buyers
Doing their first credit check and want it done right. We help you understand what a lender will actually approve before you fall in love with a property outside your range. More on our first home buyer loans page.
Auction and Private Treaty Bidders
A pre-approval that is not backed by a full credit check is just an estimate. We arrange formal, assessed pre-approval so you can bid or make an offer knowing the number is real.
Self-Employed Buyers
Two years of tax returns or BAS statements tell a different story to a payslip. We work out how a lender will actually read your income before you start house hunting on a guess.
Guarantor-Backed Buyers
Before you ask a parent or family member to go guarantor, you need a firm number. We confirm exactly how much the loan needs and how it affects the guarantor’s own position. See also our low deposit home loans page.
Property Investors
Good opportunities move fast, and existing debt complicates serviceability. We get your borrowing capacity assessed against your current portfolio, alongside our investment loans options, so you can act when the right property comes up.
Buyers Upgrading or Relocating
Selling and buying at the same time only works if you know your real budget first. We confirm your borrowing power before you list, so your next offer is not a guess.
Quick Pre-Approval vs Full Assessment: The Distinction That Actually Matters
Two things get called pre-approval in Brisbane, and only one of them means anything once you are standing in front of a vendor or an auctioneer.
A quick or online pre-approval is a self-reported estimate. Nobody checks your credit file, verifies a payslip, or confirms a single debt. It takes 24 to 48 hours and tells you almost nothing about what a lender will actually do once they look properly.
A full assessment pre-approval, the only kind we put Brisbane clients forward for, involves a genuine credit check and verification of your income, employment and liabilities before a lender commits to a figure in writing. It takes 3 to 5 business days through us, and it is the version real estate agents recognise as credible.
The Two Types of Pre-Approval at a Glance
| Quick or online pre-approval | Full assessment pre-approval | |
|---|---|---|
| Credit check | None, the figures are self-reported | A genuine credit check is run |
| Income and debts | Not verified | Payslips, employment and liabilities all verified |
| Turnaround | 24 to 48 hours | 3 to 5 business days through us |
| Lender commitment | None in writing | A written figure from the lender |
| How agents treat it | Treated as an estimate | Recognised as credible by agents and vendors |
| Safe to bid at auction | No, there is no finance clause to fall back on | Yes, this is the version we require before a client bids |
What a Lender Is Actually Assessing
Every lender, bank or non-bank, is testing the same four things: your income, your credit history, your existing debts, and your deposit.
| Category | What is needed |
|---|---|
| Identity | Two forms of ID (licence, passport or Medicare card) |
| Income | Last 3 months of payslips, or 2 years of tax returns and financials if self-employed |
| Employment | Confirmation of your current role and length of employment |
| Savings and deposit | 3 or more months of bank statements showing your deposit and genuine savings |
| Liabilities | Credit cards, car loans, personal loans, BNPL accounts and other debts |
| Assets | Other property, vehicles, savings and investments you hold |
Every lender also has to test your repayments at roughly 3% above the actual loan rate, an APRA mandated buffer that applies regardless of which bank you use. It is why two lenders can look at identical income and land on two different maximum loan amounts.
Timeframes: How Fast It Happens and How Long It Holds
Through us, a full assessment pre-approval is typically ready in 3 to 5 business days. Applying direct to a bank can take 5 to 14 days, because your file sits in a general queue rather than one we are actively managing.
Once issued, major bank pre-approvals are generally valid for 90 days. Some non-bank and digital lenders extend this to 180 days. If your search runs longer, most lenders allow a one-off extension of 30 to 60 days, provided you resupply current payslips and pass a fresh credit check.
We track your expiry date ourselves and manage that renewal, so it does not lapse mid-search without you noticing.
Why a Brisbane Auction Is No Place for a Guess
No Cooling-Off at Auction
Queensland’s standard 5 business day cooling-off period does not apply at auction. The moment the hammer falls, you are contractually bound to settle, with no finance clause and no window to walk away if the loan does not come through.
An Estimate Becomes a Liability
If a full assessment would have reduced your borrowing amount or declined you outright, an auction is the worst possible place to discover it. We will not put a client up to bid without a credit-checked pre-approval behind them.
What Can Still Move Between Pre-Approval and Settlement
Pre-approval is conditional, not guaranteed, and a handful of things can shift your final outcome.
- The bank’s valuation comes in under the contract price, reducing what they will lend against the property
- New debt appears, a car loan, a higher credit card limit, or a buy now pay later account opened after pre-approval
- Your income or employment changes, including reduced hours, a new probation period, or a job switch
- An undisclosed or forgotten liability surfaces during the formal credit check
- Lender policy or interest rates shift materially before formal approval is issued
We flag every one of these upfront, specifically so your pre-approval does not quietly unravel three weeks before settlement.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
How MC Mortgage Solutions Runs Your Pre-Approval
Before We Apply
We review your income, debts and deposit first, and tell you honestly what is realistic and with which lenders, before anything is submitted.
During Assessment
We submit one well-prepared application to the lender whose policy genuinely fits you, rather than shopping you around multiple banks and stacking enquiries on your credit file.
Once You Are Approved
We confirm your validity date, explain exactly what would change your approved amount, and manage the extension if your property search runs past 90 days.
Why Choose MC Mortgage Solutions for Your Pre-Approval
25+ Years of Combined Lending Experience
Every pre-approval benefits from two decades of reading how different lenders actually assess income, debt and deposit.
One Application, Not a Shotgun Approach
We submit a single, well-matched application instead of shopping you around multiple lenders and stacking credit enquiries on your file.
Full Assessment, Not a Guess
Every pre-approval we arrange is credit-checked and verified, the kind agents and vendors actually take seriously.
Matched to the Right Lender’s Policy
We match you to whichever lender’s servicing rules genuinely fit your income, deposit and debt position, not just whoever has the lowest rate.
Free to You
The lender pays our commission, and we are legally bound to act in your best interests regardless of who that ends up being.
We Manage Your Expiry Date
Your 90 day window is tracked by us, with renewal handled before it becomes a problem, not after.
Speak to a Brisbane Pre-Approval Specialist
Book a free, no obligation assessment, and we will tell you honestly what you are likely to be approved for and by which lender, before anything goes on your credit file.
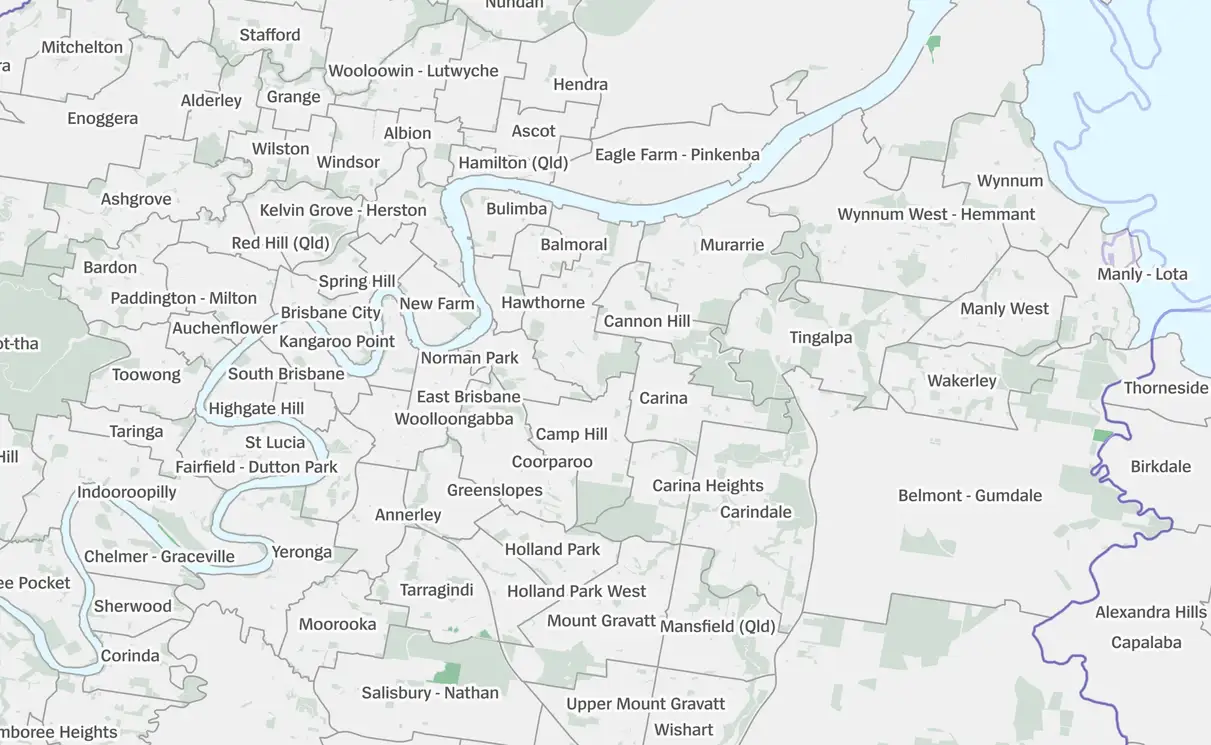
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed & Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating on Brisbane’s bayside since 2007. Brokers with 25+ years of lending experience each. |
| Best-interests duty | As a mortgage broker, we are bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Get a Pre-Approval You Can Actually Rely On
An online estimate takes two minutes and means very little in front of a vendor or an auctioneer. A full assessment pre-approval takes a few days and means the number is real. MC Mortgage Solutions compares 30+ Brisbane lenders and manages your pre-approval from first application through to a confirmed, credit-checked budget, at no cost to you.
Our All Services
Pre-approval is the first step. Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFrequently Asked Questions (FAQs)
Common questions about how long pre-approval lasts, what it does to your credit file, what documents you need and whether it holds up at auction. If yours is not here, ask us directly.
How long does home loan pre-approval last in Australia?
Most major bank pre-approvals are valid for 90 days. Some non-bank and digital lenders extend this to 180 days, and a one-off 30 to 60 day extension is often available if your search runs longer, subject to updated documents and a fresh credit check.
What is the difference between quick pre-approval and full pre-approval?
A quick or online pre-approval is a self-reported estimate with no credit check. A full assessment pre-approval verifies your income, credit file and debts before a lender commits in writing, which is what agents and vendors take seriously.
Does applying for pre-approval affect my credit score?
Yes. A full assessment pre-approval involves a hard credit enquiry, which stays on your file for 5 years. Multiple applications with different lenders in a short window can look like financial stress, which is one reason we submit a single, well-prepared application rather than shopping you around.
What documents do I need for home loan pre-approval?
Two forms of ID, 3 months of payslips or 2 years of tax returns if self-employed, 3 or more months of bank statements, and details of your existing debts and assets.
Can I make an offer with just a quick online pre-approval?
You can, but it is risky. If a full assessment would have reduced your borrowing amount or declined you, you will not find out until after you have made the offer, which is too late.
Do I need pre-approval before bidding at a Brisbane auction?
Yes. Queensland’s standard cooling-off period does not apply to auction sales, so you are contractually bound the moment the hammer falls, with no finance clause to fall back on.
Can my pre-approved amount change before settlement?
Yes. A lower valuation, new debt, a change in income or employment, or an undisclosed liability found during formal assessment can all reduce or void your pre-approval.
Is pre-approval available for self-employed buyers and investors?
Yes. We match self-employed applicants and investors to lenders on our panel whose policy reads their income and existing debt sensibly, rather than applying a one-size-fits-all servicing test.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902