 QLD Broker of the Year
Commercial Property Investment Loans Brisbane, QLD
Finance for tenanted offices, warehouses, retail and specialised assets, assessed on the lease, the tenant and your position across 30+ lenders, including SMSF options. Australian Credit Licence 394061. Locally owned in Manly since 2007, serving Greater Brisbane.
Brisbane, Queensland Commercial Property Investment Finance Specialists
MC Mortgage Solutions has arranged commercial finance from Manly, in Greater Brisbane, since 2007. A loan secured against a tenanted office or warehouse is assessed on entirely different grounds to a home loan, and we built our commercial practice around that difference rather than bolting it onto residential lending.
Our focus here is investors buying commercial property for rental income and growth, not business owners financing premises they’ll occupy themselves. That distinction changes everything from your deposit to your rate, and we handle the owner-occupied side of commercial lending on a separate commercial property loans page for exactly that reason.
Before we compare a single lender, we work through the tenant’s strength, how long the lease has left to run, the rent review terms and how exposed the property is to vacancy. Those factors decide what a lender will actually approve, long before their advertised rate becomes relevant.
We arrange commercial investment finance across Greater Brisbane, including Manly, Wynnum, Carina, Morningside, Cannon Hill and the commercial pockets through Brisbane’s inner east and bayside.
Who We Serve: Commercial Property Investors Across Brisbane
Commercial investment finance isn’t one product, and the right structure depends heavily on why you’re buying. We work with Brisbane investors across a range of starting points.
Residential Investors Moving Into Commercial
You’ve built equity and serviceability through residential property and want a different risk and yield profile. We work out how commercial fits alongside what you already hold, not as a separate, disconnected purchase.
SMSF Trustees Investing in Business Real Property
Buying a commercial property inside super is still genuinely available after the August 2026 LRBA changes, provided the property qualifies. We check that before you get attached to a particular address.
Investors Buying Into an Existing Lease
A tenanted property with a lease already in place changes what you’re actually assessing: the tenant’s strength and the time left on that lease, more than the building itself.
Investors Targeting a Specific Asset Class
Medical suites, retail strips, industrial sheds and office space are priced and financed differently by lenders. We match you to lenders who actually have appetite for the asset class you’ve chosen, not a generic commercial panel.
Small Syndicates and Joint Purchasers
Commercial property is bought jointly more often than residential is. We structure finance across multiple unrelated buyers so each party’s position and exit are clear from the start.
Investors Releasing Equity to Fund a Commercial Purchase
Using equity in an existing property as your deposit works differently for a commercial purchase than a residential one, particularly around how much of that equity a commercial lender will actually recognise.
Investment vs Owner-Occupied Commercial Loans: Why the Difference Matters
Mixing these two up before you apply is the most common mistake we see. Here’s how a lender actually tells them apart.
| Factor | Owner-Occupied Commercial Loan | Commercial Investment Loan |
|---|---|---|
| Typical deposit | 10% to 20% | 20% to 30%, more for specialised assets |
| Typical LVR | Up to 80% to 90% | Generally lower, often 65% to 75% |
| Interest rate | Generally lower | Generally higher, reflecting vacancy and tenant risk |
| Loan term | Often up to 25 to 30 years | Typically shorter, often 15 to 25 years |
| What a lender reads first | Your business’s trading performance | The lease, the tenant’s covenant, and the rental income |
| Interest deductibility | Usually not deductible, unless mixed use | Usually deductible, along with management fees, repairs and depreciation |
| Serviceability basis | Your business’s trading income | The property’s rental income and your own income combined |
These ranges move with the lender, the property and your own position. Confirm deductibility with your accountant before relying on it for tax planning.
How Lenders Assess Commercial Investment Loan Serviceability
A commercial investment loan gets assessed twice: the property, then the borrower, before the two are combined into one decision.
On the property side, lenders weigh tenant covenant strength, remaining lease term, any rent review clauses, and WALE (weighted average lease expiry), where a longer WALE generally supports a higher LVR. Rental income is only partly counted toward serviceability, with an allowance held back for vacancy and outgoings, and many lenders also check your interest cover ratio (ICR) before anything else.
On the borrower side, it’s the same fundamentals as any loan: income, credit history, debts and deposit, just assessed against a smaller panel of lenders who actually price commercial assets well.
Investment Loan for Commercial Property Options at a Glance
| Option | Typical deposit | Best suited to |
|---|---|---|
| Standard commercial investment loan | 20% to 30% | Investors with full financials and a straightforward tenanted asset |
| Low doc commercial investment loan | 30%+ | Self-employed investors without current full financials |
| SMSF business real property loan (LRBA) | 20% to 30%, fund-dependent | SMSF trustees buying a qualifying commercial asset |
| Specialist asset finance | 30%+, asset-dependent | Childcare, medical, hospitality, service stations and other specialised securities |
Deposit requirements shift with tenant strength, lease length and property type. We confirm your actual range once we know the specific property.
How Our Commercial Property Investment Loan Process Works
Free Asset Review
We look at the property, the lease, and your own financial position together, before anything is submitted anywhere.
Lease and Tenant Assessment
We work through tenant covenant, remaining lease term and WALE, the same way a lender will, so there are no surprises mid-application.
Lender and Structure Match
We match you to a lender whose appetite and pricing suit this specific asset class, including SMSF and specialist lenders where relevant.
Pre-Approval
A confirmed position before you’re negotiating hard against a vendor or competing at auction.
Settlement
We manage the application through to settlement, including any security structuring needed to avoid unnecessary cross-collateralisation.
Speak to a Brisbane Commercial Property Investor Specialist
Book a free asset review, and we’ll tell you in one conversation what a lender will actually approve against the lease, the tenant and your own position.
SMSF Commercial Property Investment: What Changed on 10 August 2026
From 10 August 2026, a self-managed super fund can only use a limited recourse borrowing arrangement (LRBA) to buy real property if it qualifies as business real property, land and buildings used wholly and exclusively in a business, with new LRBA borrowing for residential property now stopped. A shop, warehouse, office or similar asset generally still qualifies, even with an unrelated tenant, and existing LRBAs or contracts exchanged before that date continue under the previous rules.
What fails the test is anything that isn’t predominantly business use, a mixed-use property with a separately let residential component, for example. This is general information, not financial, legal or tax advice, so confirm whether a specific property qualifies with your accountant or SMSF specialist before exchanging a contract, and talk to us about structuring the loan once that’s confirmed.
The Risks of Commercial Investment Lending Most Buyers Don’t See Coming
Vacancy costs more than it does in residential, often running months rather than weeks, with re-leasing bringing agent fees, a fit-out contribution or a rent-free period before income resumes. That risk compounds with a short WALE: the shorter the lease remaining at purchase, the weaker your position looks at the next refinance or sale, affecting both valuation and lender appetite.
Cross-collateralisation can creep in quietly when equity from an existing property funds your deposit, tying that property to the new loan as combined security and complicating an independent sale or refinance later.
Specialised assets, childcare centres, service stations, pubs and similar, are financed by a narrower lender pool, typically at a lower LVR, so factor that into your deposit planning from the outset.
Why Choose MC Mortgage Solutions for Commercial Investment Finance
25+ Years of Lending Experience
Reading leases and tenant covenant for Brisbane commercial investors, not just processing applications.
We Assess the Lease First
Tenant strength, lease term and WALE get checked before we start comparing lenders, not after.
SMSF and Specialist Lender Access
We know which lenders still have appetite for business real property and specialised assets, and which have pulled back.
We Avoid Unnecessary Cross-Collateralisation
Your existing property stays separate from your new purchase wherever the structure allows it.
Free to You
Our service costs you nothing. The lender pays our commission, and we’re legally required to act in your best interests.
A Referral-Driven Reputation
90% of our clients come through referrals from investors we’ve already helped settle a commercial purchase.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
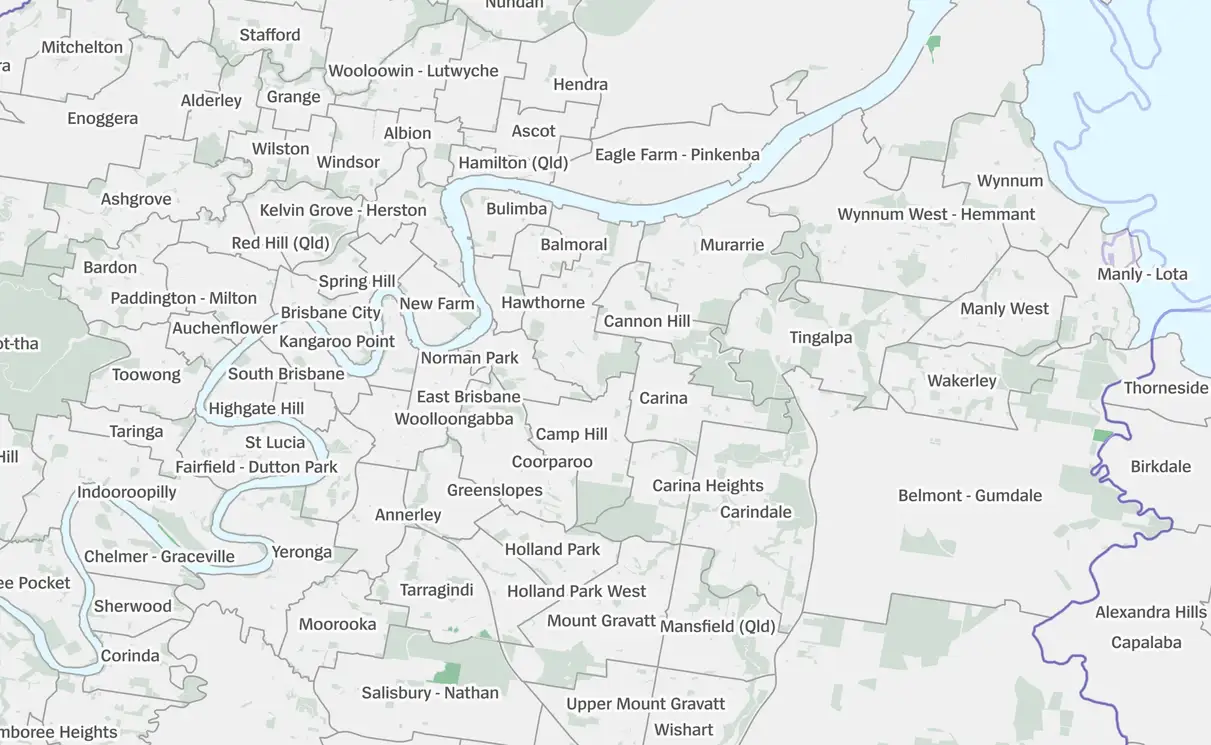
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed and Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating from Manly since 2007. Brokers with 25-plus years of combined lending experience. |
| Industry body | Member of the Mortgage & Finance Association of Australia (MFAA). |
| Recognition | Awards include QLD Broker of the Year, the MFAA Excellence Award (2016) and Platinum Elite Broker (2021 to 2022). |
| Best-interests duty | As a mortgage broker, we’re bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Find Out What a Commercial Investment Loan Would Actually Look Like
Not a generic rate comparison, a structure built around the actual lease, tenant and asset you’re looking at. MC Mortgage Solutions compares 30+ lenders, including SMSF and specialist options, and manages your commercial investment loan from first assessment through to settlement, at no cost to you.
Frequently Asked Questions (FAQs)
Common questions about deposits, SMSF rules, WALE, rental income and structuring a commercial investment loan in Brisbane. If yours is not here, ask us directly.
What’s the difference between a commercial investment loan and an owner-occupied commercial loan?
An owner-occupied loan funds premises your own business uses, assessed against your business’s trading income. An investment loan funds a property leased to a tenant, assessed against the rental income and lease, and generally needs a larger deposit.
How much deposit do I need for a commercial investment property in Brisbane?
Typically 20% to 30%, though this shifts with tenant strength, lease length and property type. Specialised assets can need 30% or more.
Can I still buy commercial property through my SMSF?
Yes, provided it qualifies as business real property under the rules that took effect 10 August 2026. This is general information, not advice, so confirm your specific property with your SMSF specialist or accountant before exchanging.
What is WALE and why does it matter for financing?
Weighted average lease expiry is the average time remaining across a property’s leases, weighted by rental income. A longer WALE generally supports a higher LVR, since the income is seen as more secure.
Is rental income counted in full when a lender assesses my application?
No. Most lenders only count a portion of gross rental income, holding back an allowance for vacancy and outgoings, similar to how residential investment income is treated.
Can I buy a commercial investment property jointly with someone else?
Yes. Commercial property is bought jointly more often than residential, and we structure the loan so each buyer’s position and exit are clear from settlement.
Does cross-collateralisation affect commercial investment loans too?
Yes. If you use equity in an existing property as your deposit, it can end up tied to the new purchase as combined security unless the loan is specifically structured to avoid it.
Are specialised commercial assets like childcare centres or service stations harder to finance?
Generally yes. These assets are financed by a smaller panel of lenders, usually at a lower LVR, so we factor that into your deposit planning from the start.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902