 QLD Broker of the Year
Self-Employed Home Loans in Brisbane, QLD
MC Mortgage Solutions arranges self-employed home loans in Brisbane from our Manly office. We compare more than 30 lenders and match your ABN, tax returns and BAS to each policy, so you learn your options before you apply. Our service costs you nothing. Call 07 3893 3208 to start.
Brisbane Mortgage Broker for Self-Employed Home Loans
Running your own business can make your income look smaller on paper than it feels. Depreciation and uneven months confuse lenders who expect a payslip. MC Mortgage Solutions Brisbane arranges self-employed home loans for local borrowers.
Our Brisbane Mortgage Broker’s panel covers more than 30 lenders, and we compare them on your behalf. Then we line up your ABN history, tax returns and BAS against each lender's rules.
We check features such as offset accounts and lenders mortgage insurance. You hear your options before any application goes to a lender.
Our team has more than 25 years of lending experience with sole traders and directors. We work from your accountant's records, so your application matches your lodged returns. From our Manly office, we serve the Bayside, the Redlands Coast and Brisbane East.
Lenders pay us, so you pay no fee for our advice. Call 07 3893 3208 or book a 15-minute call to see which documents suit your business.
What Our Self-Employed Home Loan Service Includes
Our service covers everything from your first question to settlement day. You deal with one broker team. We deal with the lenders.
We start with your income, trading history and goals, then explain how a lender will read them.
You get a list of the documents to gather and the gaps to fix first.
We compare lender policies and loan features, including offset accounts, split loans and lenders mortgage insurance, so the loan fits your cash flow.
We prepare and submit the application, answer the lender's questions and manage conditions through to settlement.
We do not lend money ourselves, so we have no product to push. We do not give tax or accounting advice, because your accountant keeps charge of your returns and we work from the records they prepare. No broker can promise approval. Every lender makes its own decision, and each one sets its own rules for self-employed income.
Self-Employed Home Loans for Buying, Refinancing, Investing and Building
Self-employed borrowers can apply for the same home loans Brisbane buyers choose. The paperwork behind them is what changes. Each job below has its own page with more detail.
Buying a Home as a Sole Trader, Director or Partner
Buying a home on business income works best when you check your documents first. We match your records to lenders before you shop, so you know your budget before you bid. The same method applies to first home buyer loans Brisbane, next home loans Brisbane and home loan pre-approval Brisbane.
Refinancing With Your Latest Tax Return
Another completed financial year may change how a lender reads your business, so a refinance mortgage Brisbane review lets you test that.
Buying an Investment Property
An investment loan adds rental income and existing debts to your business income. Lenders weigh all of it together, so we check how each piece reads before you apply for investment loans Brisbane lenders offer.
Building or Renovating Your Home
A build adds staged payments to the usual income checks. Construction loans Brisbane lenders offer release funds to the builder at each stage, so we plan the timing with you.
How Lenders Assess Self-Employed Home Loans in Brisbane
Lenders assess self-employed income through four main routes, and the route you use changes how much paperwork you need. The table shows what four lenders published on 20 November 2026. Policies change, so we check each one again when we prepare your application.
| Route | What the lender looks at | Published example | Worth knowing |
|---|---|---|---|
| Standard two-year assessment | Two years of business and personal tax returns, the latest notice of assessment and two years of business financial statements | Westpac and St.George | You need more than two full financial years of trading and a registered ABN. Sole traders only need personal tax returns |
| One-year assessment | The latest year of tax returns, the latest notice of assessment and your business liabilities | Westpac and St.George. National Australia Bank (NAB) considers one year of financial statements at an LVR of 80 percent or less | Westpac and St.George still ask for two full financial years of trading. NAB applies other terms and conditions |
| Fast Track | Your last two personal ATO notices of assessment, with no business financials | Westpac and St.George | Both ask for a deposit of 20 percent of the property value |
| Alt doc | ABN and GST registration for at least six months, a declaration of financial position, and six months of business bank statements, six months of lodged BAS or an accountant's letter | Pepper Money | The lender still completes a full credit assessment. Eligibility criteria apply to the accountant's letter |
The sources are the lenders' own self-employed home loan pages, accessed 20 November 2026. The table shows published policy, not an offer of credit. Your result depends on your full circumstances.
How Long You Have Traded Changes Your Options
Your trading history decides which routes stay open. Use this list as a starting point, then talk to us about your own dates.
Under six months of trading limits your options. Pepper Money's alt doc loan asks for six months of ABN and GST registration. Lodging your first records may help more than applying early.
Six to twelve months of trading may open alt doc options. You would need six months of BAS or business bank statements and a declaration of financial position.
About one year of records suits some lenders. NAB looks for at least one year of solid income records. It may use one year of financial statements at an LVR of 80 percent or less. Westpac and St.George still ask for two full financial years of trading.
Two years or more of trading gives you the widest choice of lenders. Standard assessment, one-year assessment and Fast Track all become options.
Use two counts to decide. Count your months of ABN and GST registration, and your full financial years of trading. Under six months, expect to wait. From six months, ask about alt doc. From one year of records, ask which lenders accept a single year of financials. From two full financial years, ask about Fast Track and one-year assessment.
Who Self-Employed Home Loans Suit
Self-employed home loans suit anyone who earns through an ABN, and four situations come up often.
Sole traders with one lodged return may need a second year of returns. Some lenders accept one return with extra evidence.
Company directors may pay themselves a wage and leave profit in the company. Lenders may look at the company and your personal returns together.
Partners and trust beneficiaries need clear records of their share of income, so your accountant's statements matter here.
Newer business owners with strong recent income may still have alt doc options once your ABN and GST registration reach six months.
Sometimes waiting is the better plan. A short wait can widen your choices when you have not lodged a return yet, or when your ABN is under six months old. We tell you when waiting beats applying.
Talk Through Your Options With Our Manly Team
Tell us how long you have traded and what records you hold. We will show you which routes fit and what to fix first. Call 07 3893 3208 or book a 15-minute call.
Documents Lenders Ask Self-Employed Borrowers For
Documents for Self-Employed Home Loans in Brisbane
Lenders ask for documents that prove your income, your trading history and your cash flow, and each lender sets its own mix. You need to meet all of it. These nine documents appear on the lender pages we checked.
Personal tax returns and ATO notices of assessment
The income you reported to the ATO
Where it appears: NAB and Westpac
Business tax returns
Business income for a company, partnership or trust
Where it appears: NAB and Westpac
Profit and loss statement and balance sheet
Current trading and business assets
Where it appears: NAB
Financial statements signed by a registered tax agent or accountant
An accountant's view of your recent years
Where it appears: Pepper Money
Business activity statements (BAS)
Sales, GST and PAYG reported to the ATO, not profit
Where it appears: NAB and Pepper Money
ABN and GST registration details
How long your business has operated and registered
Where it appears: NAB and Pepper Money
Personal and business bank statements
Deposits, spending and conduct
Where it appears: NAB and Pepper Money
Accountant's letter
Your accountant's summary of your position, if the lender accepts it
Where it appears: Pepper Money
Declaration of financial position
Your own written statement of your financial position
Where it appears: Pepper Money
The home loan approval checklist covers the personal documents you also need, such as ID and savings.
How Lenders Read Sole Trader, Company, Trust and Partnership Income
Your business structure changes which returns a lender wants. Westpac and St.George ask sole traders for personal tax returns only. Companies, partnerships and trusts also supply business returns, and the standard route adds business financial statements. Westpac accepts a registered ABN for sole traders, partnerships, companies and trusts.
Depreciation and write-offs can lower your taxable income, even when business is going well. Westpac and St.George suggest keeping proof of those expenses and your business liabilities. Tell your accountant you plan to apply, so they can send extra information quickly.
Company directors can ask their accountant how wages, dividends and profit show in the returns. Different lenders read that mix differently. We compare their policies before you apply, so your documents suit the right lender.
What Helps a Self-Employed Application
NAB lists several habits that strengthen an application. The other lender pages we checked point the same way.
Keep business and personal accounts separate, so your bank statements show where the money came from.
Hold a registered ABN and keep your GST registration current.
Explain one-off costs, such as equipment purchases, in a short note.
Show steady income, because lenders may average changing income across a set period or use a lower recent figure when your income has dropped.
Save a deposit of 20 percent where you can. NAB notes this helps you avoid lenders mortgage insurance.
Pay down other debts where possible, because lenders weigh debts against income.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
Our Process for Self-Employed Home Loans
Our process runs in five steps, and we manage each one with you.
A free conversation comes first, covering your business, trading history and goals. Then we explain how a lender will read your records.
We check your records against lender requirements, then tell you what to gather or fix.
We compare loans from our panel of more than 30 lenders and show you the choices side by side.
Next, we prepare a file for the lender you choose and answer its questions as they come.
We manage lender conditions and coordinate settlement. Later, we review your loan with you.
What Affects the Cost of a Self-Employed Home Loan
Your cost depends on the loan you choose, not on whether you run a business. We do not quote a rate here. Lenders change rates often, and they set each one from your full profile and your chosen loan.
- A larger deposit lowers your loan to value ratio. Pepper Money says rates and fees depend on factors including the LVR.
- Lenders mortgage insurance usually applies when your deposit is under 20 percent, which is common on low deposit home loans Brisbane buyers take.
- Your document route can change the price. St.George says some lenders only offer a low doc loan with a higher rate or larger deposit. That applies when a borrower cannot supply standard documents.
- Offset accounts, split loans and fees change what you pay over time.
- Queensland stamp duty adds to your upfront costs, and the stamp duty calculator Queensland gives you a figure to budget for.
We compare the whole cost of each loan, fees included. Run the borrowing power calculator for a first estimate. Then talk to us about your own numbers.
Why Self-Employed Borrowers Choose MC Mortgage Solutions
Lenders pay our commission, so you get broker advice without a fee.
Our panel includes more than 30 lenders and over 200 loan products. A no from one lender does not end your search.
Our brokers work with business owners on home, investment and business lending, so we know what business records look like.
You can meet us in Manly or online. We also hold mobile appointments across Brisbane and the Bayside.
Income protection is a separate service. Self-employed income protection Brisbane cover replaces part of your income if illness or injury stops you working.
Where We Help Self-Employed Borrowers
We serve self-employed borrowers from our Manly office at 138 Kingsley Tce, and you can book in person or online. Our brokers also hold mobile appointments across Brisbane and the Bayside. We help clients around Manly and Wynnum, across the Redlands Coast and in Brisbane East.
Local pages cover mortgage broker Manly and mortgage broker Wynnum, and the full list shows all the areas we serve. We have no office outside Manly.
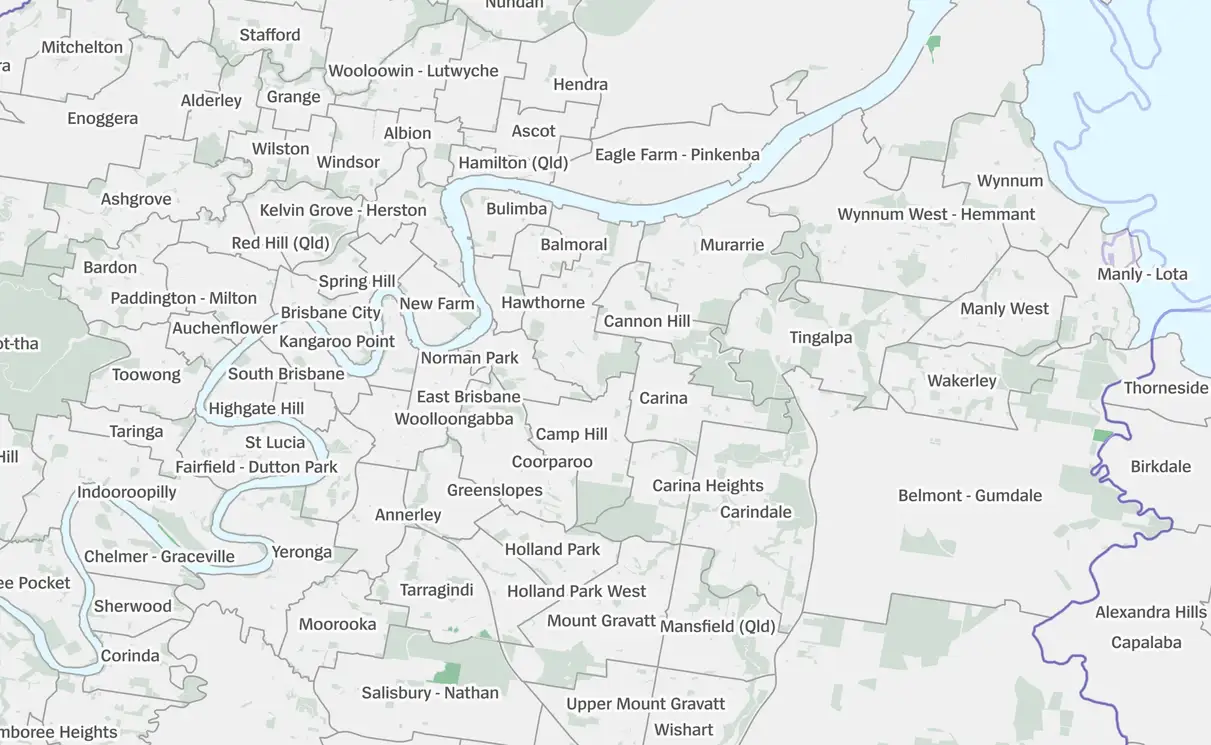
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed and Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating from Manly since 2007. Brokers with 25-plus years of combined lending experience. |
| Industry body | Member of the Mortgage & Finance Association of Australia (MFAA). |
| Recognition | Awards include QLD Broker of the Year, the MFAA Excellence Award (2016) and Platinum Elite Broker (2021 to 2022). |
| Best-interests duty | As a mortgage broker, we’re bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Start Your Self-Employed Home Loan Conversation
Call 07 3893 3208 or book a 15-minute call with our Manly team. Have your ABN details and latest tax return ready if you can. We will explain your options in plain English and tell you what to do next. Our service costs you nothing.
Our All Services
Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFAQs on Self-Employed Home Loans
Can I get a home loan if my income changes from month to month?
Yes, but lenders look closely at the pattern. NAB says lenders may average your income across a set period, and they may use a lower figure if your recent income dropped. Contracts or long-term client agreements can show stability. We help you collect those contracts.
Can I use BAS instead of tax returns?
Some lenders accept BAS instead of tax returns. NAB lists BAS as an option when tax returns are not available. Pepper Money's alt doc loan accepts six months of lodged BAS. A BAS reports GST and PAYG to the ATO, so it shows sales activity rather than profit. Each lender sets its own rules.
Is an accountant's letter enough for a self-employed home loan?
An accountant's letter does not replace your other documents. Pepper Money asks for six months of GST and ABN registration and a declaration of financial position. It then adds one of three items, and the accountant's letter is one of them. Eligibility criteria apply to the letter. NAB says a letter summarising your position may help a standard application.
What is the difference between low doc and alt doc home loans?
Low doc is an older term, and alt doc is the name Pepper Money uses today. Pepper Money says low doc meant different things from lender to lender. It says its alt doc loans still get a full credit assessment. St.George does not offer low doc loans. For low doc home loans in Brisbane, we check which lenders offer an alternative route.
Will I pay a higher interest rate as a self-employed borrower?
It depends on the lender and your document route. Westpac and St.George say you can get the same loans and rates as salary earners. That applies when you borrow in your own name and they can assess your taxable income. A lender that uses alternative documents may price differently. We compare actual loan offers before you choose.
Can I apply if my partner earns a PAYG wage and I run a business?
Yes, you can apply with a partner who earns a PAYG wage. Lenders assess both incomes, and a steady wage can support the application. Westpac says Fast Track can still apply when one or both applicants are self-employed. We work out which lender policy suits your mix of income.
Does a mortgage broker cost self-employed borrowers anything?
No, our service is free to you because lenders pay our commission. We still explain every fee and feature before you commit to a loan.
What should I bring to my first call?
Bring your ABN details and your latest tax return or notice of assessment. Add recent BAS, profit and loss statements or business bank statements if you have them. We will tell you which extra documents suit your trading history.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902