 QLD Broker of the Year
Business Property Loans in Brisbane, QLD
MC Mortgage Solutions arranges a business property loan in Brisbane when you buy or refinance the premises your business uses. We compare more than 30 lenders and match your trading records, the property and the entity that will own it to each policy. Our service costs you nothing. Call 07 3893 3208 to get started.
Brisbane Mortgage Broker for Business Property Loans
Paying rent on a building you could own can feel like a one-way street. Lenders then ask for trading records, a valuation and a structure that fits the property. MC Mortgage Solutions Brisbane arranges business property loans for owners in that position.
Our brokers test your financials and the property against the policies of more than 30 lenders. We then show the loan terms, repayment types and fees side by side before you decide. You hear your options before any application reaches a lender.
We work with your accountant and solicitor, so your loan fits your structure and your contract dates. We explain each lender's terms in plain English, including fees and conditions.
From our Manly office, we serve the Bayside, Wynnum, the Redlands Coast and Brisbane East. Lenders pay our commission, so you pay no fee for our advice. Call 07 3893 3208 and tell us which premises you have in mind.
Our Business Property Loan Services in Brisbane
One broker team looks after you from your first question until settlement day. The four services below cover each step of buying or owning your premises.
Business Premises Purchase Loans in Brisbane
We arrange the loan when you buy the building your business rents today, or move to a bigger or second site. Your lease dates and contract timetable decide how fast we move. Our guide to buying commercial property in Brisbane covers due diligence and local costs.
Key Features
- We compare lender policies, loan terms and fees for owner-occupied premises.
- We check how lenders read the debt on a second site next to your first.
- We prepare and submit the application to the lender you choose.
- We answer lender questions and manage conditions through to settlement.
Benefits
- You know your options before you make an offer.
- Your loan lines up with your lease end and contract dates.
- One team talks to the lenders while you run the business.
Business Premises Pre-Approval in Brisbane
A pre-approval tells you what a lender may fund before you sign a contract. It can help when your landlord plans to sell or a property moves fast.
Key Features
- We review your trading records, existing debts and current lease.
- We check early which entity should borrow.
- We list any gaps a lender may query.
Benefits
- You see a clearer borrowing range before you inspect properties.
- You face fewer surprises when the lender asks for records.
- You get more time to act when a sale timetable is short.
Business Premises Refinance and Equity Release in Brisbane
A refinance can change your lender, your loan term or your repayment type. Equity in your premises, or in your home, can also pay for a deposit on another property. Our guide to using home equity in Australia explains the basics.
Key Features
- We compare your current loan against lender policies and fees.
- We review repayment type and loan term, including interest-only where a lender offers it.
- We check the equity a lender may release against the property.
Benefits
- You see the cost of switching before you commit.
- You can free cash for a deposit or renovations.
SMSF Business Premises Loans in Brisbane
Your SMSF can buy business premises and lease them to your business when super law and the fund's deed allow it. We arrange the borrowing, and your SMSF adviser confirms the fund can buy. Read our SMSF commercial property loans Brisbane guide first.
Key Features
- We compare lenders that accept SMSF borrowing side by side.
- We check lender rules, such as Pepper Money's corporate trustee requirement.
- We arrange pre-approval and the loan structure for the fund's purchase.
Benefits
- You hear lender limits before your fund commits.
- The loan structure matches the fund's lease to your business.
We are a broker, not a lender, so we have no loan product of our own to sell. We do not give tax, legal or self-managed super fund (SMSF) advice. Your accountant, solicitor and SMSF adviser keep charge of those parts. No broker can promise approval, because every lender makes its own decision.
Owner-Occupied or Investment, Which Business Property Loan Fits?
An owner-occupied loan fits when your business uses the property, and an investment loan fits when a tenant pays rent. Premises can be an office, shop, warehouse, workshop or clinic, and lenders ask for different paperwork depending on who uses the building.
| Question | Owner-occupied business premises | Investment property |
|---|---|---|
| Who uses the building | Your business | A tenant |
| What the lender checks first | Your trading records and cash flow | The lease and the tenant |
| Extra paperwork | Business financials and your current lease | Signed lease agreements |
Many buildings do not fit one box. If your business uses half the space and a tenant rents the rest, lenders differ on how they classify the loan. We check each lender's policy against your floor plan and lease.
Our guide on owner-occupied vs investment commercial property loans compares the two in more depth. For purchases you plan to let out, see our commercial property loans Brisbane page.
Talk Through Your Premises Plan With Our Manly Team
Tell us the property, your lease dates and how long your business has traded. We will show you which lenders suit and what to prepare first. Call 07 3893 3208 or pick a time for a 15-minute call.
What Lenders Publish About Business Property Loans
Limits on the loan to value ratio (LVR) differ a lot from lender to lender, so we rely on the lenders' own pages. Four lenders published the following on 20 November 2026. Policies change, and we check each one again when we prepare your application.
| Lender | What the lender publishes | Worth knowing |
|---|---|---|
| BOQ Specialist | Up to 100 per cent of the purchase price for owner-occupied practice premises, and up to 85 per cent for an investment property with no lenders mortgage insurance. Interest-only for up to 10 years | The page speaks to practice owners, so check whether your business type qualifies |
| Pepper Money | A full doc option that uses one year of tax returns, loan terms from 1 to 30 years and cash-out options. Information correct as of 17 September 2026 | Eligibility criteria and lending limits apply |
| Liberty | A low rate commercial loan that it calls ideal for business premises, with interest-only for up to 8 years and a low doc option | Liberty's footnotes set the conditions, so we read them before we compare |
| Westpac | Investment loans for non-trading entities of up to 70 per cent LVR on loans to $3 million, and 65 per cent above $3 million | This covers investment property, so it shows how limits change with the loan purpose |
SMSF lending sits on its own limits. Pepper Money publishes a maximum LVR of 80 per cent for business real property. BOQ Specialist publishes up to 90 per cent for owner-occupied practice premises. Liberty publishes up to 80 per cent of property value.
Broker guides online quote very different limits, so we treat them as opinion and check the lender's page. We took every figure from the lenders' own pages on 20 November 2026. These figures describe published policy, not an offer of credit. Your own result depends on your full financial position.
How Much Cash You Need to Buy Business Premises
You need cash for your deposit, Queensland transfer duty, GST where it applies, and valuation, legal and lender fees. Each item changes your budget. We list them with you before you sign a contract.
Your deposit depends on the lender, the property type and any extra security you offer.
Transfer duty follows the Queensland Revenue Office rates, and the table below shows two worked examples.
GST can change the cash you need on settlement day.
Valuation, legal and lender fees sit on top, and we show each fee when we compare loans.
Queensland transfer duty
Dutiable value $800,000
Queensland transfer duty
Dutiable value $1,200,000
The Queensland Revenue Office applies its general duty rates to commercial property, and it last updated those rates on 25 June 2026. Your solicitor confirms the dutiable value for your contract. Use the stamp duty calculator for your own figure.
The Australian Taxation Office (ATO) says the sale of commercial premises generally carries GST, and the seller may use the margin scheme. A sale of a going concern can be GST-free when the buyer and seller meet specific conditions. Your accountant confirms how GST affects your settlement cash and whether you can claim it back.
We do not quote a rate on this page. Lenders set each rate from your business, the property and your loan. Our guide to commercial property loan rates in Brisbane explains what moves it. Test your repayments against today's rent with the loan repayment calculator.
Documents Lenders Ask Business Owners For
Lenders want proof of your trading history, your cash flow and the property. Each lender sets its own mix. The table lists examples from Westpac's broker page and from our own checklist.
Latest 12 months of ATO statements, including the integrated client account
Whether you owe the ATO anything
Where it appears: Westpac
One-year individual tax return and notice of assessment
The income you reported
Where it appears: Westpac
Accountant-prepared financial statements or your latest business tax return
Your profit and trading position
Where it appears: Westpac
12 months of business activity statements (BAS)
Sales and GST reported to the ATO, not profit
Where it appears: Westpac
Three months of statements for any loan you refinance
How you manage repayments today
Where it appears: Westpac
Contract of sale or agent's details, plus your current lease
The price, the property and the rent you pay now
Where it appears: Our checklist
Signed lease agreements, if you will let part of the building
The rent the property earns
Where it appears: Westpac
Westpac says BAS can support some applications up to $1.5 million, and the other items change with the lender. We confirm the list for your chosen lender before you gather anything. Ask your accountant for the tax and BAS records early.
Who Should Own the Building
Structure comes first. The entity that borrows changes who signs, who guarantees and which lenders accept the deal. You can buy through your trading company, a family trust, a separate property company, in your own name or through your SMSF.
When a separate entity owns the building and leases it to your business, lenders may want to read that lease. Your accountant and solicitor advise on the best owner. We then check that your chosen lender accepts that structure before you sign a contract. If you need an accountant, ask about our accounting service.
When a Business Property Loan Suits You
A business property loan suits owners who want to stop paying rent and own the building instead. Four situations come up often.
You rent your premises and a lease renewal or a landlord sale is close.
Your business has outgrown its site and needs a bigger or second one.
You already own premises and want to refinance or release equity.
Your fund can buy a building and lease it to your business.
Timing matters on the lender side too. Pepper Money offers a full doc option that uses one year of tax returns, so a business with no return yet may have fewer choices. We tell you when a short wait widens your options.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
Our Process for Business Property Loans
A business property loan moves through five steps, and you see each one.
A free conversation comes first, covering your business, your lease and the property you have in mind.
We review your records and tell you what to gather or fix.
We compare loans across our panel of more than 30 lenders and lay the options out together.
Next, we prepare the file for your chosen lender and answer its questions as they come.
We manage conditions and the valuation, then coordinate settlement with your solicitor. After settlement, we review the loan with you.
Why Business Owners Choose MC Mortgage Solutions
Our advice costs you nothing, because the lender you choose pays us.
Our panel includes more than 30 banks and specialist lenders and over 200 loan products. If one lender declines your structure, another may accept it.
We work alongside your accountant and solicitor, so your structure, contract and loan line up.
Meet us at our Manly office or talk online. Brokers can also travel to you for a mobile appointment in Brisbane and the Bayside.
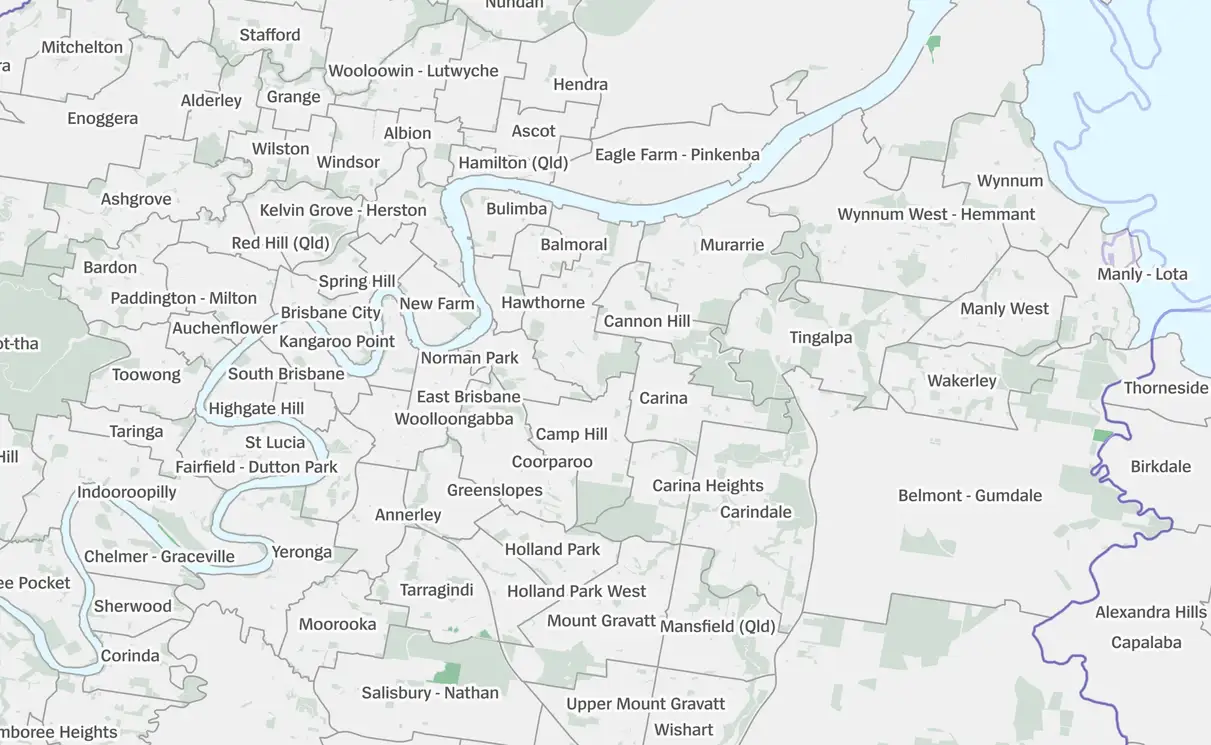
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed and Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating from Manly since 2007. Brokers with 25-plus years of combined lending experience. |
| Industry body | Member of the Mortgage & Finance Association of Australia (MFAA). |
| Recognition | Awards include QLD Broker of the Year, the MFAA Excellence Award (2016) and Platinum Elite Broker (2021 to 2022). |
| Best-interests duty | As a mortgage broker, we’re bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Start Your Business Property Loan Conversation
Call 07 3893 3208, or book a 15-minute call with a Manly broker. Bring your latest tax return and your current lease if you can. We explain your options in plain English, then set out your next step. You pay nothing for our advice.
Our All Services
Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFAQs on Business Property Loans
Can I get a business property loan to buy the premises I rent now?
Yes. Many lenders finance owner-occupied premises, and your trading records carry most of the weight. Lenders look at your financials, the property and your ownership structure. Tell us your lease end date and any landlord sale plans so we match the loan to your timetable.
How much deposit do I need for owner-occupied business premises?
It depends on the lender, the property type and your security. BOQ Specialist publishes up to 100 per cent of the purchase price for owner-occupied practice premises, and other lenders publish lower limits. Duty, GST and fees sit on top of any deposit, so we budget the full cash figure with you.
Can I borrow 80 per cent of a business property's value?
Some lenders publish 80 per cent or more, but the limit depends on your loan type and property. Pepper Money publishes a maximum 80 per cent LVR for SMSF business real property. BOQ Specialist publishes higher figures for owner-occupied practice premises. We check the current limit with your chosen lender.
What counts as owner-occupied if I let part of the building?
Lenders differ, so the answer depends on your lender. A building that your business mostly uses may qualify as owner-occupied with one lender and not another. Send us your floor plan and any lease, and we check each lender's policy before you make an offer.
Does GST apply when I buy business premises?
Often. The ATO says the sale of commercial premises generally carries GST, and a seller may use the margin scheme. A sale of a going concern can be GST-free when the buyer and seller meet set conditions. Ask your accountant how it affects you.
Can my SMSF buy my business premises?
Possibly. Strict rules apply. Pepper Money lends to corporate trustees only for SMSF business real property. Your SMSF adviser decides whether your fund can buy and lease to your business. We then arrange the finance and compare lenders that accept SMSF loans.
How long must my business have traded?
Each lender sets its own rule. Pepper Money offers a full doc option that uses one year of tax returns, and many lenders look at two years of records. If your trading history is short, we tell you which options exist and whether waiting would help.
Does a business property loan carry the same protections as a home loan?
Often not. ASIC says the National Credit Act covers loans used mainly for personal, domestic or household purposes, and loans for business premises usually fall outside that. We explain the terms in plain English, and your solicitor reviews the contract before you sign.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902