 QLD Broker of the Year
Equity Release Home Loans Brisbane, Queensland
Access the equity in your home through a standard refinance, with your LVR, LMI and lender purpose rules checked first across 30+ lenders. Australian Credit Licence 394061. Locally owned in Manly since 2007, serving Brisbane’s bayside and Redlands.
Top-Rated Home Equity Release Specialists Serving Greater Brisbane
MC Mortgage Solutions is based in Manly, QLD, and has been providing equity release refinancing services across Greater Brisbane since 2007. We help homeowners access the equity built up in their property through a standard home loan refinance, without needing a reverse mortgage or handing over a share of their home.
We arrange equity release the way most Brisbane homeowners actually need it: a cash-out refinance against your existing home loan, used to fund a renovation, a deposit for your next property, debt consolidation, or another genuine purpose.
We start by working out how much equity you can access without pushing your loan-to-value ratio past 80% or triggering Lenders Mortgage Insurance, then compare lenders on how they treat the purpose of your funds, because evidence requirements and borrowing limits vary significantly between them.
Our brokers regularly work with homeowners right across Greater Brisbane, from Manly and Wynnum through to Birkdale, Wellington Point, Carina, Morningside and the wider Redlands.
Who We Serve: Equity Release Homeowners Across Brisbane, QLD
Releasing equity suits different goals, and the right structure depends on what the funds are for and how soon you need them. We work with Brisbane homeowners across a range of equity release situations, not just straightforward refinances.
Homeowners Funding a Renovation
Whether it’s a kitchen upgrade or a full extension, we work out how much equity your current valuation supports and whether a staged drawdown tied to the build or a single lump sum suits your project better.
Homeowners Using Equity as a Deposit for Their Next Property
Moving into an investment property or upgrading your own home usually starts with equity in what you already own. We calculate how much is genuinely available and what servicing a new loan against it will actually cost.
Homeowners Consolidating Debt Into One Repayment
Credit cards and personal loans sit at rates well above a mortgage. We check whether rolling that debt into your home loan through equity release genuinely lowers your overall cost, not just your monthly repayment.
Parents Releasing Equity to Help Their Kids Buy
A deposit gifted from equity in your own home can get an adult child into the market years sooner. We work out how much you can release without compromising your own position, and how a lender will treat a deposit that didn’t come from savings.
Self-Employed Homeowners Needing Business Capital
Fluctuating income reads differently to a lender once you’re asking them to release equity rather than simply approve a purchase. We know which lenders will work with your current financials and which will fixate on one lower-income year.
Homeowners Comparing Equity Release to a Reverse Mortgage
If you’re over 60 and have been steered toward a reverse mortgage, it’s worth checking whether you still qualify for a standard refinance first. We lay out both options honestly so you can see which one actually costs less over time.
Equity Release vs a Reverse Mortgage: Know the Difference Before You Choose
Equity release is often used as an umbrella term, and it’s worth knowing which product you’re actually being offered. A standard equity release, what this service covers, is a cash-out refinance: you borrow against your home’s value under normal lending criteria, at a standard interest rate, with regular repayments like any other home loan.
A reverse mortgage is a different product entirely. It’s generally available from around age 60 (some lenders from 55), lets you access roughly 15% to 45% of your home’s value depending on your age, and requires no regular repayments. Interest capitalises onto the loan balance instead, and the debt is repaid when the home is sold, you move into aged care, or you pass away. Every reverse mortgage in Australia must include a Negative Equity Guarantee, meaning you can never end up owing more than the home is worth when it’s sold, and lenders must ensure you receive independent legal advice before signing.
Most homeowners under 60 with steady income are better served by a standard equity release refinance, it’s cheaper over time because the balance doesn’t sit compounding untouched for years. We’ll tell you plainly which path actually suits your age, income and goals rather than defaulting to whichever product happens to pay us more.
How Much Equity You Can Actually Access
Most lenders let you release equity up to 80% of your property’s current value, minus what you still owe, without having to provide evidence of what the funds are for. Some lenders go further, up to 90%, but only if you can show exactly how the money will be used.
Borrow beyond that 80% mark and Lenders Mortgage Insurance (LMI) usually applies, even if you didn’t pay it on your original loan, because the lender is now carrying more risk against your property’s value. We check your numbers against a current valuation, not what you paid years ago, before telling you what’s realistically available.
What Lenders Want to Know Before Releasing Your Equity
Most lenders will release $10,000 to $50,000 in equity without asking what it’s for, simply on the basis that you’ve disclosed a purpose. Above that, expect to provide evidence, renovation quotes, a contract of sale, or a schedule of debts being consolidated, before the funds are approved.
On top of the purpose check, every lender must test your ability to repay the larger loan at roughly 3 percentage points above your actual rate, the same APRA-mandated buffer applied to any home loan. A bigger equity release means a bigger loan to service, so we run this test before you apply, not after a lender comes back with a smaller number than expected.
Equity Release Home Loan Options at a Glance
| Option | Best for | Typical access | Key consideration |
|---|---|---|---|
| Standard cash-out refinance | Renovations, debt consolidation, a deposit for your next purchase | Up to 80% LVR without evidence, 90% with evidence | LMI usually applies above 80% LVR |
| Line of credit or offset restructure | Homeowners who want funds available but not yet spent | Set against an approved limit | Interest typically only charged once drawn |
| Family equity release (gifted deposit) | Parents helping an adult child into their first property | Same 80%/90% LVR rules as standard cash-out | Lender will ask how the deposit was sourced |
| Reverse mortgage | Homeowners aged 60+ who don’t want or can’t service regular repayments | Roughly 15% to 45% of home value, based on age | No repayments required, interest capitalises, Negative Equity Guarantee applies |
Why Choose MC Mortgage Solutions for Equity Release in Brisbane
Licensed and Bound to Put You First
Licensed under Australian Credit Licence 394061 and bound by the MFAA’s best interests duty, so every equity release recommendation is required to put you first, not the lender.
25+ Years of Combined Lending Experience
Reading how different lenders treat cash-out purpose, LVR limits and evidence requirements.
Purpose First, Then Lender
We ask what the funds are for before we ask which lender, and we’ll tell you honestly if a reverse mortgage suits your age and goals better than a standard refinance.
No Surprises at Settlement
We model your repayments at the lender’s required buffer rate and flag any Lenders Mortgage Insurance before you apply.
Nothing Upfront
Our service costs you nothing upfront. The lender pays our commission once your refinance settles, with no obligation to proceed after your first conversation.
Locally Based in Manly
Serving Greater Brisbane’s bayside and Redlands since 2007, not a call centre working from a script.
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
What to Expect Once You Start
Equity and Serviceability Review
We work out how much equity you can access, your resulting LVR, and what the new repayment will look like at the APRA buffer rate.
Lender and Purpose Comparison
We compare how 30+ lenders treat your intended use of funds and recommend whichever structure gets you the most usable equity for the least cost.
Application and Settlement
We manage the application, any valuation required, and the settlement timing so your refinance completes smoothly.
Your Local Contact for Equity Release Advice in Brisbane
Every equity release situation is different, and the fastest way to know where you stand is a conversation, not a calculator. Reach out directly and we’ll walk through your numbers, your LVR position, and what’s genuinely available before you commit to anything.
The Risks of Releasing Equity You Should Know About
Releasing equity increases your loan balance, and if you extend your loan term back out to 25 or 30 years to keep repayments manageable, you can end up paying more interest over the life of the loan than the equity released actually cost you upfront. We model the total interest cost, not just the new monthly repayment, before you commit.
If your property’s value has moved less than expected, or you’re releasing a large amount, your LVR can climb higher than planned and trigger LMI you didn’t budget for. We check this against a current valuation estimate first, so there are no surprises when the formal valuation comes back.
Folding short-term debt, like a car loan or credit card, into a 25 to 30 year home loan can lower your monthly repayment but means you’re paying it off far slower and with far more interest than the original debt would have cost. We weigh that trade-off honestly rather than just chasing the lower repayment figure.
Service Areas We Serve Across Greater Brisbane & Bayside
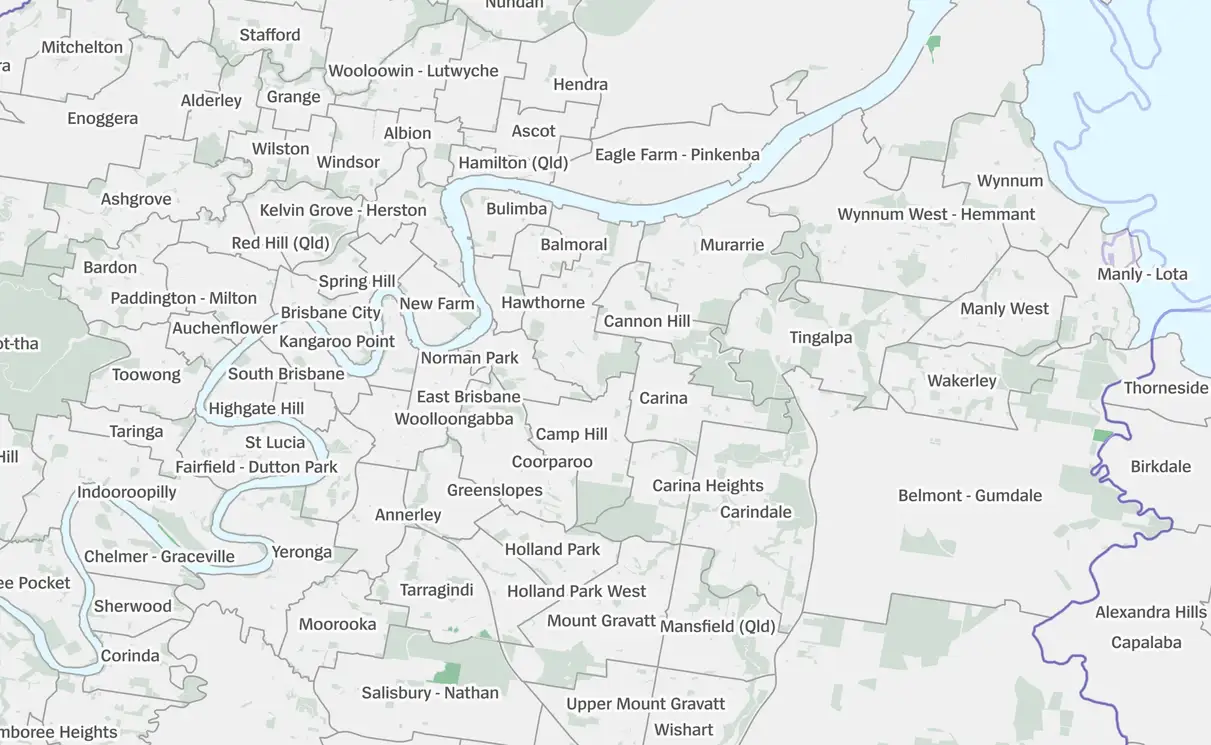
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed and Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating from Manly since 2007. Brokers with 25-plus years of combined lending experience. |
| Industry body | Member of the Mortgage & Finance Association of Australia (MFAA). |
| Recognition | Awards include QLD Broker of the Year, the MFAA Excellence Award (2016) and Platinum Elite Broker (2021 to 2022). |
| Best-interests duty | As a mortgage broker, we’re bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Know Exactly What Your Home Equity Can Do For You
Not every lender will release the same amount, or ask for the same evidence, so the figure one broker quotes you isn’t always the figure another can actually deliver. MC Mortgage Solutions compares 30+ Brisbane lenders, checks your LVR and serviceability upfront, and gives you a straight answer on what’s genuinely available, at no cost to you.
Frequently Asked Questions (FAQs)
Common questions about usable equity, valuations, redraw versus refinance, loan terms and releasing equity in Brisbane. If yours is not here, ask us directly.
What’s the difference between a redraw and an equity release refinance?
A redraw lets you access extra repayments you’ve already made on your current loan, often instantly and at no extra cost. Equity release is different, it’s a full refinance that unlocks new borrowing against your property’s growth in value, not money you’ve already paid in.
Is an equity release home loan in Brisbane the same as a cash-out refinance?
Yes, “equity release” and “cash-out refinance” describe the same product in the Brisbane market, borrowing against your home’s current value and taking the difference as usable cash. The terms are used interchangeably by most lenders and brokers.
How much usable equity do I actually have in my Brisbane home?
Your usable equity is generally 80% of your property’s current value minus what you still owe, calculated against a fresh valuation, not your original purchase price. We run this against a current Brisbane valuation rather than an online estimate.
Can I use an offset account instead of releasing equity?
An offset account only reduces the interest on money you’ve already saved, it doesn’t create new funds. If you need new money for a renovation, a deposit or debt consolidation, releasing equity through a refinance is the option that actually provides that cash.
Can I release equity from my home to fund an investment property deposit?
Yes, using released equity as a deposit for an investment property is one of the most common reasons Brisbane homeowners refinance. We calculate how much is genuinely available and factor in how servicing both loans will be assessed.
Do home equity loans in Brisbane require a new property valuation?
Yes, every lender requires a current valuation, desktop or full, before releasing equity, since your usable amount is calculated against today’s value, not what you paid for the property.
Is a staged drawdown available for renovation-funded equity release?
Yes, several lenders offer a staged drawdown structure for renovation funding, releasing funds as the build progresses rather than as a single lump sum, which can reduce the interest you pay while the project is underway.
What happens to my loan term when I release equity?
Most refinances reset your loan term, often back out to 25 or 30 years, which can lower your immediate repayment but increase the total interest paid over the life of the loan. We model this trade-off before you commit.
Can self-employed homeowners release equity for business capital?
Yes, though lenders assess self-employed income differently when the purpose is business capital rather than a standard purchase. We know which lenders will work with your current financials without fixating on a single lower-income year.
Will releasing equity affect my portfolio if I already own multiple properties?
It can, particularly if any of your properties are cross-collateralised. We review your full portfolio structure before recommending how to release equity, so one change doesn’t complicate your other loans.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902