 QLD Broker of the Year
Low Deposit Home Loans Brisbane: Buy With as Little as 2% to 5% Down
Brisbane low deposit mortgage brokers. Buy with a 5% deposit and no LMI through government schemes, guarantor loans or 30+ lenders, at no cost to you.
About Us: Low Deposit Mortgage Brokers Serving Greater Brisbane
MC Mortgage Solutions is based in Manly QLD 4179 and has been arranging low deposit home loans across Greater Brisbane since 2007. We help buyers who are not short on income, they are short on the 20% deposit most people assume they need.
We arrange low deposit finance including the First Home Guarantee, the Family Home Guarantee, guarantor backed lending and standard low deposit loans, for buyers who do not fit the traditional deposit mould. We compare lender policies on deposit schemes and LMI waivers, not just headline rates, then handle the scheme paperwork so a government guarantee application does not become another form you have to decode yourself.
We work with buyers across Greater Brisbane, including Manly, Manly West, Wynnum, Lota, Birkdale, Wellington Point, Thornlands and Redland Bay.
Who We Serve: Low Deposit Buyers Across Brisbane
Low deposit lending works differently depending on your situation. We work with Brisbane buyers who do not have a traditional 20% deposit saved, matching each one to the pathway that actually fits them.
First Home Buyers
Strong income, limited savings. Under the First Home Guarantee, eligible buyers can purchase with a 5% deposit and no Lenders Mortgage Insurance, up to the current $1,000,000 price cap for Brisbane, Gold Coast and Sunshine Coast, subject to eligibility. See our first home buyer loans page for the full picture.
Single Parents
Raising kids solo and ready to buy. The Family Home Guarantee lets eligible single parents and legal guardians purchase with as little as a 2% deposit, subject to place availability each financial year.
Guarantor-Backed Buyers
Family security, not family debt. A parent or close relative can guarantee part of your loan, helping you avoid LMI or borrow above 80% LVR without handing over any cash themselves.
Essential Workers and Professionals
Select lenders offer reduced deposit or LMI waived packages for certain professions, including some healthcare, legal and accounting roles. We know which lenders offer these and who genuinely qualifies.
Renters Building a Deposit
Close, but not quite there yet. We help you work out the fastest realistic path, whether that is a low deposit loan now or a genuine savings plan timed against your target price.
Next Home Buyers with an Equity Gap
Selling and buying rarely line up perfectly. If your sale proceeds do not cover the full deposit on your next home, a low deposit or bridging structure can close the gap without waiting years to rebuild it. More detail on our next home loans page.
What Counts as a Low Deposit Home Loan in Greater Brisbane
Most lenders treat 20% of the purchase price as a standard deposit, because it keeps your loan at or under an 80% loan to value ratio (LVR). A low deposit home loan is anything above that, typically a 10% deposit (90% LVR) or a 5% deposit (95% LVR), and in a couple of specific QLD schemes, as little as 2%.
The trade off is Lender’s Mortgage Insurance (LMI), which applies once you borrow above 80% LVR, unless your loan sits inside a government guarantee that removes it. We cover both paths below, alongside our standard home loans Brisbane options.
What Each Deposit Size Actually Looks Like
Example only, illustrative, on a $650,000 property. This is a starting point, not a loan offer. Your actual deposit requirement depends on the lender, the property, and which scheme you qualify for.
| Deposit size | LVR | Deposit amount | LMI payable? |
|---|---|---|---|
| 20% (standard) | 80% | $130,000 | No |
| 10% | 90% | $65,000 | Yes, unless waived |
| 5% | 95% | $32,500 | Yes, unless under a no-LMI scheme |
| 2% (Family Home Guarantee or Boost to Buy only) | 98% | $13,000 | No, guarantee or shared equity applies |
How We Help You Buy With a Lower Deposit
Government 5% Deposit Scheme (First Home Guarantee)
For eligible first home buyers, we structure your loan under the federal First Home Guarantee, so you can buy with a 5% deposit and pay no LMI at all, with Housing Australia guaranteeing the rest.
Family Home Guarantee (2% Deposit)
For single parents and legal guardians with a dependent child, this guarantee allows a purchase with just a 2% deposit and no LMI, and you do not need to be a first home buyer to qualify.
QLD Boost to Buy Shared Equity
Queensland’s own shared equity scheme lets eligible first home buyers in with a 2% deposit, with the state government taking an equity share in return. Places are limited and allocated in rounds, so we check current availability for you.
Guarantor and Family Pledge Loans
If a scheme’s price cap or your eligibility does not fit, a family member’s equity can cover your deposit shortfall as security, avoiding LMI without them handing over cash.
Standard Low Deposit Loans With LMI
For investors, repeat buyers and anyone outside the schemes above, we compare 90% and 95% LVR loans across our panel and work out whether capitalising the LMI into your loan makes sense for you.
Free Pre-Approval
Get pre-approved against the right deposit strategy, so you can make an offer with confidence instead of guessing what you will be assessed on.
Your Low Deposit Options at a Glance
Current as at September 2026. We confirm your exact eligibility in the first conversation.
| Option | Min. deposit | LMI | Who it suits | QLD price cap |
|---|---|---|---|---|
| First Home Guarantee | 5% | None | First home buyers, no income cap since Oct 2025 | $1,000,000 Brisbane, Gold Coast, Sunshine Coast; $700,000 rest of QLD |
| Family Home Guarantee | 2% | None | Single parents or guardians with a dependent child | Same regional caps as above |
| Boost to Buy (QLD shared equity) | 2% | None | First home buyers, income capped, first home only | $1,000,000, limited places |
| Guarantor or family pledge loan | 0% to 5% | Avoided via security | Buyers outside scheme caps or eligibility | Set by lender policy |
| Standard low deposit loan | 5% to 10% | Applies, can be capitalised | Investors, repeat buyers, non first home purchases | Set by lender policy |
The First Home Guarantee no longer has an income cap or a limit on the number of places, a change that took effect on 1 October 2025. Boost to Buy does still cap income at $155,000 for singles and $232,000 for couples or single parents, and its places are allocated in rounds rather than open ended.
Understanding LMI: What It Costs and How to Avoid It
Lender’s Mortgage Insurance protects the lender, not you, if you default and the loan cannot be recovered in full. It applies once your LVR passes 80%, and the premium is usually a one off cost you can pay upfront or add to your loan balance.
Ways We Help You Reduce or Avoid It
- Buying under the First Home Guarantee or Family Home Guarantee removes LMI entirely for eligible buyers
- A guarantor arrangement can lift your effective deposit above 80% LVR without any cash from you or your family
- Some professions and lenders offer LMI waivers or discounts at 85% to 90% LVR, and we check your panel eligibility for these
- Capitalising LMI into your loan lowers your upfront cost but adds interest over the life of the loan, so we model both ways before you decide
Indicative LMI Costs by Property Value
Indicative only. Actual premiums vary by lender and are quoted at application.
| Property value | LMI at 90% LVR (10% deposit) | LMI at 95% LVR (5% deposit) |
|---|---|---|
| $500,000 | approx. $14,000 | approx. $17,000 |
| $600,000 | approx. $23,000 | approx. $26,000 |
| $700,000 | approx. $27,000 | approx. $31,000 |
Reviews That Reflect Our Service and Results


Our Real Client Testimonials on YouTube
How Our Low Deposit Home Loan Process Works
Free Chat
We map your deposit, income and which schemes or guarantor options you could use.
Deposit Strategy
We work out whether a government guarantee, a guarantor loan, or a standard low deposit loan fits your situation best.
Borrowing Power
We calculate what you can realistically borrow across multiple lenders under that strategy.
Lender and Scheme Match
We line up the lender whose policy suits your deposit path, not just their rate.
Pre-Approval
A confirmed budget, so you can make an offer or bid with confidence.
Approval and Settlement
We manage the lender, the scheme paperwork if one applies, and keep everything moving through to the keys.
Why Brisbane Buyers Choose MC Mortgage Solutions for Low Deposit Finance
25+ Years of Lending Experience
Structuring low deposit and scheme based finance for Brisbane buyers for over two decades.
We Compare Policies, Not Just Rates
We assess deposit scheme eligibility and LMI waivers lender by lender, not just who has the lowest headline rate.
Free to You
Our service costs you nothing. The lender pays our commission, and we are legally required to act in your best interests.
We Handle the Scheme Paperwork
Government guarantees and shared equity applications are our job to navigate, not another form for you to decode.
A Referral-Driven Reputation
90% of our clients come through referrals from Brisbane buyers we have already helped into their first home.
Talk to a Brisbane Low Deposit Home Loan Specialist
Book a free, no obligation chat, and we will tell you in one conversation which deposit path fits you and what you can borrow.
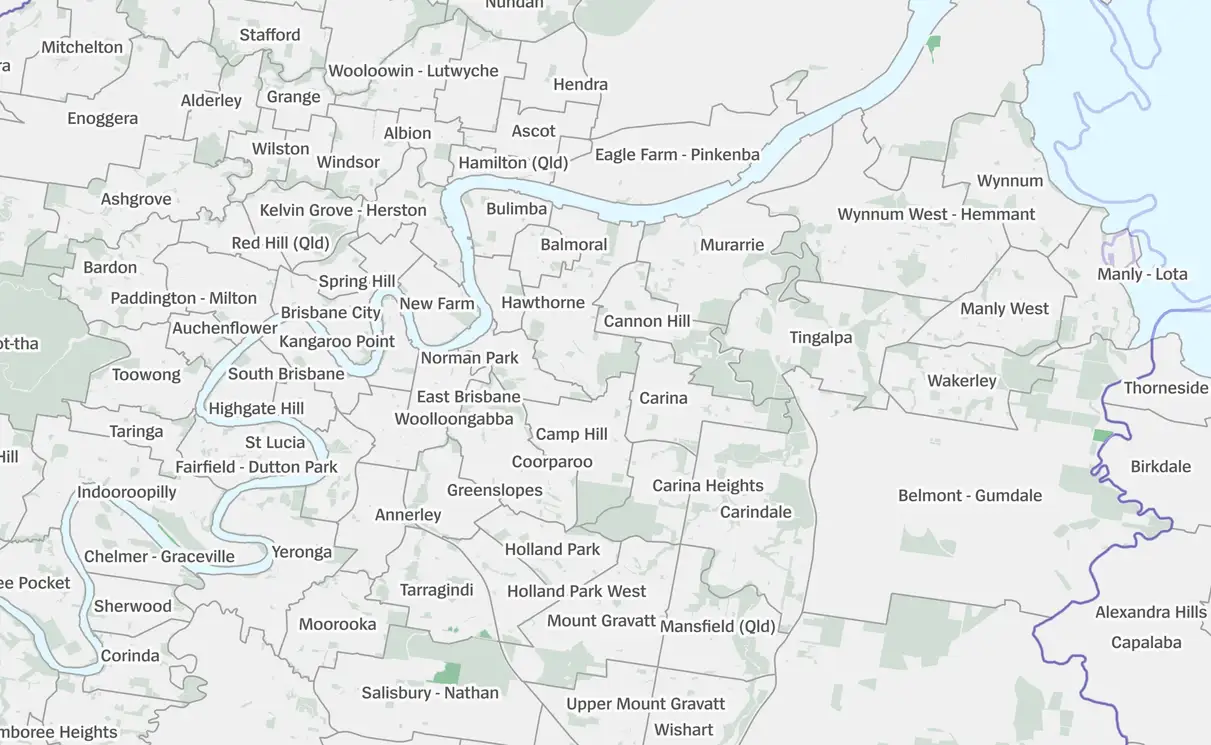
Service Areas We Serve Across Greater Brisbane & Bayside
From our Manly office we meet clients across the Bayside, the Redlands Coast and Brisbane’s east. Choose your suburb for local lending guidance.
Looking for the Best Mortgage Broker Near Me in Brisbane? Get Trusted Guidance.
- Mobile appointments across Brisbane and Bayside
- Free Mortgage and personalised loan guidance
- Trusted by 90 % referral clients
Manly & Wynnum
Redlands Coast
Map: Gompk, CC BY-SA 4.0, via Wikimedia Commons (cropped)
Qualified, Licensed & Local
| Category | Details |
|---|---|
| Licensing | MC Mortgage Solutions Pty Ltd · ACN 128 555 902 · Australian Credit Licence 394061. Matthew Carr, Credit Representative. |
| Experience | Locally owned and operating on Brisbane’s bayside since 2007. Brokers with 25+ years of lending experience each. |
| Best-interests duty | As a mortgage broker, we are bound by law to act in your best interests, a duty that applies to every broker in Australia. |
Our Lenders
We compare more than 200 loan products from 30+ banks and specialist lenders, including:
Find Out How Little Deposit You Actually Need
Do not let a 20% deposit assumption keep you out of the market. There are at least five paths into a Brisbane home with less, and we will tell you which ones you qualify for in one call. MC Mortgage Solutions compares 30+ Brisbane lenders and manages your low deposit loan from pre-approval through to settlement, at no cost to you.
Our All Services
Low deposit lending is one part of what we do. Explore the rest of our Brisbane lending and financial services.
Financial Services
Income protection, investment, general insurance, accounting and self-managed super.
Explore financial servicesRefinance
Review your current loan against the market and switch when the numbers stack up.
Explore refinancingFrequently Asked Questions (FAQs)
Common questions about deposits, LMI, government guarantees and what our service costs a low deposit buyer. If yours is not here, ask us directly.
What is the lowest deposit I can buy a home with in Queensland?
As little as 2%, if you qualify for the Family Home Guarantee or QLD Boost to Buy. Most other buyers work with 5% under the First Home Guarantee or a guarantor loan, or 10% under a standard low deposit loan.
Do I have to pay LMI on a low deposit loan?
Only if you are borrowing above 80% LVR outside a government no-LMI guarantee. A First Home Guarantee, Family Home Guarantee, or a guarantor loan can all remove it.
Can I get a low deposit loan if I am not a first home buyer?
Yes. The Family Home Guarantee does not require first home buyer status, and standard low deposit loans with LMI are available to investors and repeat buyers too.
Does the First Home Guarantee still have an income cap?
No. Income caps and place limits on the First Home Guarantee were both removed from 1 October 2025, so eligibility now comes down to first home buyer status and the property price cap for your area.
What is the price cap for the First Home Guarantee in Brisbane?
$1,000,000 for Brisbane, the Gold Coast and the Sunshine Coast. The rest of Queensland is capped at $700,000.
Can my parents help without giving me cash?
Yes, through a guarantor or family pledge loan. Their property equity secures part of your loan instead of a cash gift, which can remove LMI without them transferring any money.
How much does LMI actually cost?
It varies by lender and LVR, but as a guide, expect roughly $14,000 to $31,000 on a $500,000 to $700,000 property at 90% to 95% LVR. We get you an exact figure before you commit to a lender.
Do I need genuine savings to get a low deposit loan?
Some standard lenders want part of your deposit built up over time rather than gifted. Loans under the First Home Guarantee, Family Home Guarantee or a guarantor structure often relax or remove this requirement.
Visit or Call Our Manly Office
MC Mortgage Solutions is based on Kingsley Terrace in Manly and meets clients across Greater Brisbane and the Bayside, in person or online.
| Monday to Friday | 8 am to 5 pm |
| Saturday | 9 am to 5 pm |
| Sunday | 9 am to 5 pm |
Australian Credit Licence 394061 | ACN 128 555 902